All Posts By

Donna Cournoyer

Your College FAFSA Prep List: What to Have Ready Now That It’s Open

If you’ve been waiting for the FAFSA to open, stop waiting — it’s live. This year the form actually opened about a week early, ahead of the October 1 deadline set by the FAFSA Deadline Act. For families who’ve been burned by a rocky FAFSA season in years past, that’s genuinely good news: an earlier, smoother launch means more time before the priority deadlines that matter most on state and school financial aid pages.

What’s Actually Better This Year

A few changes are worth knowing about before you start, because they’ll save you time and, in some cases, worry:

  • Pre-populated fields for returning filers. If you filed last year, a good chunk of your information carries forward, which cuts the time the form takes substantially.
  • Reusable parent information. If you have more than one child applying to college this year or next, a parent’s financial information can now be reused across multiple students’ applications instead of re-entered from scratch each time.
  • Plainer language throughout. The Department of Education stripped out a lot of the financial-aid jargon that used to make certain questions genuinely confusing to answer correctly.
  • Small family businesses and farms are excluded from asset calculations. If your household owns a family business with fewer than 100 employees, a family farm, or a commercial fishing operation, that value is no longer counted against you in the need calculation.

One more detail worth knowing: this cycle’s FAFSA runs on 2025 tax data under the “prior-prior year” rule, so you’re not scrambling to finish this year’s return before you can file.

Before You Sit Down: The Prep List

Saying the FAFSA “is open” and “we’re ready to sit down and file it” are two different things. Think about this: the families who get through the FAFSA in one sitting aren’t the ones who are especially tech-savvy — they’re the ones who gather everything first. Here’s what I want every family on my list to have in hand before they open that first screen.

Set aside twenty minutes before you ever open the form itself and gather these. It’s the single biggest thing you can do to keep the process from dragging into three separate sessions.

  • A StudentAid.gov account for the student — and for each parent who’ll be a contributor. Every contributor needs their own FSA ID, and verification can take a day or two, so this is the very first thing to do, not an afterthought.
  • Social Security numbers for the student and for any parent who has one (there’s a path for parents without an SSN, so that alone shouldn’t hold a family back from filing). A common mistake is transposing one digit or using the wrong child’s number. Be careful!
  • Consent to the IRS data transfer. Every contributor must consent to having federal tax information pulled directly from the IRS — without it, the form can’t be processed, no matter how accurately the rest is filled in.
  • Current account balances, not estimates — cash, checking, savings, and investment account statements, valued as of the day you actually sign the form.
  • Records of child support received in the prior calendar year, if that applies to your household.
  • Your school list. You can list up to twenty schools on the FAFSA, and you need at least one to submit — so have the full list ready, not just the favorite.

Don’t Stop at the FAFSA: The CSS Profile Is a Different Animal

If any school on your list is a private college, there’s a good chance the FAFSA isn’t the whole assignment. About 200 mostly private colleges also require the CSS Profile, a separate form run by the College Board that determines eligibility for the school’s own institutional aid — not federal aid. Confuse the two, or assume filing one covers the other, and a family can miss out on exactly the kind of grant money a private school’s price tag depends on.

A few things make it genuinely different, not just a second copy of the same homework:

  • It costs money. $25 for the first school, $16 for each additional one — though it’s free for U.S. undergrads with family adjusted gross income up to $100,000, anyone who already qualified for an SAT fee waiver, or a student who is an orphan or ward of the court under 24.
  • It digs deeper into assets. Home equity, small business and family farm value, and even a non-custodial parent’s finances after divorce can all come into play — details the FAFSA either doesn’t ask about or, this year, specifically excludes.
  • It opens on the same date, but each school sets its own deadline. The 2027-28 CSS Profile opened October 1, 2026, same as the FAFSA — but don’t assume the filing windows line up after that; check every school’s own priority date.

The practical takeaway: pull the list of schools first, check each one’s financial aid page for “CSS Profile required,” and budget both the time and the (sometimes waivable) fee before assuming the FAFSA alone tells the story.

A Common Mistake: Waiting

Families wait. They wait for a final decision on where their child is applying, they wait for a “better time,” they wait until a deadline is staring them down. Don’t.

Filing the FAFSA has nothing to do with being accepted anywhere — it’s simply how a family becomes eligible to be considered for aid at all the schools on that list. The earlier it’s in, the earlier your family shows up in line for aid that, at many schools, is awarded on a rolling or limited basis.

And if something on the form turns out to be wrong after you’ve submitted it? It can be corrected. That’s not a reason to rush through it carelessly, but it is a reason not to let a single unanswered question hold up the whole submission for weeks.

The Bottom Line

The FAFSA being open earlier and running smoother this year is a real gift of time — don’t spend it waiting. Get every contributor’s account set up this week, gather your actual account balances, and get the form filed well before any priority deadlines start appearing on your target schools’ financial aid pages.

If you want my best advice on filling out these forms; be honest, don’t overestimate, don’t overshare.

Good luck!

-DC

Digital Estate Planning: The Gap in an Otherwise Excellent Plan

Most of the estate plans we review are in good shape. The will is current, the trust is funded, the beneficiary designations match the documents, the health care proxy names someone who will actually answer the phone.

Then we ask a simple question — if something happened to you tomorrow, could the person you named get into your email? — and the room goes quiet.

That silence is what digital estate planning is about. It is the least glamorous part of your plan and, increasingly, the part most likely to cause your family real trouble.

What We Mean By “Digital Assets”

The term is broad enough to be unhelpful, so it’s worth breaking into four categories that behave very differently.

Assets with independent monetary value. Cryptocurrency and self-custodied digital holdings, domain names, monetized channels or online storefronts, gaming accounts with resale value, and intellectual property in digital form — manuscripts, photograph libraries, software. All of these have independent monetary value.

Assets with sentimental value only. Twenty years of photographs in iCloud or Google Photos. Text message threads with a parent who has died. Video. Recorded voicemails. These have no dollar value and are frequently the thing families grieve losing most.

Accounts that are keys to everything else. Your primary email address is the single most important digital asset you own, because it is the password-reset destination for your bank, your custodian, your insurer, and your tax preparer. Your password manager and your phone number sit in the same category. None of these have value in themselves; all of them can be used to access valuable assets.

Obligations, not assets. Auto-renewing subscriptions. A business domain that lapses. Cloud storage that stops being paid for and gets purged. Two-factor authentication tied to a phone line a family member “helpfully” cancels three days after the funeral. These are obligations that in many cases should be serviced for a period after a loved one passes.

Digital estate planning means deciding, in advance and in writing, who gets access to each of these, how they will get in, and what you want done with them.

Why This Is Genuinely Hard

It would be reasonable to assume that if your executor has a death certificate and letters of appointment, the rest is paperwork. It isn’t, for three independent reasons.

Federal privacy law was written to keep people out. The Stored Communications Act prohibits providers from disclosing the contents of electronic communications to third parties. It was drafted in 1986 to protect users from snooping, and it makes no exception for a grieving spouse. Separately, the Computer Fraud and Abuse Act makes unauthorized access to a computer system a federal offense. This is why “my wife knows my passwords” is not a plan — it is, at best, an arrangement that works only as long as nobody scrutinizes it.

Terms of service usually say the account is not transferable. You do not own your Apple ID or your Gmail account in the way you own your car. You hold a license, personal to you, that a company’s contract terms may say terminates at death. Custodians have historically leaned on those terms to refuse access even when the estate’s authority was clear.

Most states have the statute that solves this. The Revised Uniform Fiduciary Access to Digital Assets Act (RUFADAA) — a model law giving executors, trustees, conservators, and agents under a power of attorney a defined legal path to digital assets — has been adopted by forty-eight states and the District of Columbia. Massachusetts and Louisiana have not adopted this statute.

The practical consequence is important, so I want to state it plainly: in these states, the authorization language in your own documents is doing more work than it would in almost any other state. Elsewhere, a statute supplies a default when the documents are silent. Here, silence is closer to a dead end.

It’s also worth understanding the hierarchy RUFADAA establishes, because the platforms follow it regardless of what your state has enacted:

  • The first priority goes to an online tool — a legacy contact setting inside the platform itself.
  • The second priority goes to your will, trust, or power of attorney. Only if both are silent do the company’s terms of service control.
  • That ordering surprises people: a legacy contact you designated on your phone in 2023 outranks the will you signed in 2024.
  • Consistency between the two matters.

Four Ways This Goes Wrong

  1. Eleven years of litigation over one email account. John Ajemian, a Massachusetts man, died in a bicycle accident in August 2006 at age 43 without a will. His siblings who were appointed personal representatives of his estate, asked Yahoo for access to the email account he had used as his primary address. Yahoo refused without a court order. The dispute went to the Massachusetts Supreme Judicial Court, which held in October 2017 that the Stored Communications Act does not bar a provider from disclosing contents to personal representatives, who can give lawful consent on the decedent’s behalf. That ruling was a meaningful win — but it did not hand the family the account. Yahoo’s separate argument that its terms of service permitted refusal went back down for further proceedings. Eleven years, an SJC opinion, and the underlying question of can the family read their brother’s email was still not cleanly resolved.
  2. Ninety-seven percent of an estate behind a password nobody had. Matthew Mellon, a banking heir, died suddenly in April 2018 at 54. Roughly $193 million of his estate — about 97% of it — was held in the cryptocurrency XRP. Mellon had been deliberately careful about security: he split holdings across multiple cold wallets, stored credentials in different physical locations, and held some accounts under other people’s names. He had never shared the map with anyone, and his will did not mention digital assets at all. His estate spent years unable to reach the asset that was supposed to pay its taxes and creditors. The security architecture that protected him from hackers protected the assets from his own children.
  3. A court order for a card game. In August 2015, David Bush died of lung cancer in British Columbia. His widow Peggy, then 72, had the passcode to their shared iPad but not his Apple ID password. When she tried to reinstall a card game, she couldn’t. Over two months, her daughter supplied Apple with the device serial numbers, a copy of the will leaving everything to Peggy, and a notarized death certificate — the same documents that had already been sufficient to transfer the house and the car. Apple’s answer was that recovering the password would require a court order. The family only got a different answer after a CBC consumer-affairs program intervened. Note the scale here: this was not a fortune. It was a game on a tablet, and it still required a news organization to resolve.
  4. The ordinary version, which we see most often. A client is hospitalized. The agent under her durable power of attorney has full legal authority over her finances and no ability to use it, because every login attempt triggers a verification code sent to a phone that is in a drawer at the hospital, locked, with a passcode nobody knows. Nothing here involves crypto or litigation. It is just a competent fiduciary, an unambiguous document, and a six-digit code — and the code wins.

Steps You Can Take Now

None of this requires a lawyer, and most of it can be done in a single afternoon.

Build an inventory. List your accounts by category: email, financial, cloud storage, social, subscriptions, business, and anything holding cryptocurrency. You want the account name, the provider, the login identity, and a note on what you want done with it — preserve, transfer, or close. You do not need to write down passwords, and mostly you shouldn’t.

Use a password manager and turn on its emergency access feature. This is the single highest-value step on this list. A reputable password manager becomes one door instead of two hundred, and most offer an emergency or legacy access function that grants a person you designate entry after a waiting period you set. One master credential, stored securely, replaces the inventory of passwords you were about to write on paper.

Solve the two-factor problem explicitly. This is the failure point people miss. Make sure your inventory records where second factors live — which phone number, which authenticator app, where the printed backup codes are. Tell your family, in writing, not to cancel your phone line until your fiduciary says so.

Set your platform legacy tools. These take minutes and, according to the hierarchy above, they carry first priority.

  • Apple: Settings → your name → Sign-In & Security → Legacy Contact. Apple generates an access key; give a copy to your contact and store one with your estate documents. Your contact will also need a death certificate. Note the limits — legacy access is read-only, excludes purchases and stored passwords, and expires roughly three years after Apple approves the request.
  • Google: Inactive Account Manager, at myaccount.google.com/inactive. Choose an inactivity window of 3, 6, 12, or 18 months, name up to ten people, and select exactly which data each receives. It is not available on Google Workspace accounts, so use your personal account.
  • Facebook and Instagram: Settings → Memorialization Settings. Name a legacy contact, or elect deletion. Understand that a legacy contact manages a memorialized profile — they never receive your login or your private messages.

Write a letter of instruction. Separate from your legal documents, unsigned and informal, this is where you say what you want: which photographs matter, whether the Facebook account should be memorialized or deleted, who should be told, what should simply be closed. It carries no legal force, and it is often the most useful page in the file.

Do not put passwords in your will. A will admitted to probate becomes a public record. Credentials belong in a password manager or a sealed document your fiduciary can find — and your will should point to their location, not contain them.

What To Ask Your Estate Planning Attorney to Do

When you next meet with counsel, these are the specific requests worth making. Attorneys who do this work regularly will have language ready; those who don’t will appreciate a client who knows to ask.

Add express digital asset authority to every document, not just the will. Incapacity is the more common scenario, so your durable power of attorney needs this authority as much as your will does. Ask that your will, revocable trust, and durable power of attorney each grant your fiduciary explicit authority to access, control, manage, distribute, copy, and dispose of your digital assets.

Include specific consent to disclosure of electronic communications content. This is the clause that matters most, and it is separate from general digital asset authority. Ask for language expressly consenting, for purposes of the Stored Communications Act, to disclose the content of your electronic communications to your fiduciary. Without it, a provider’s most reliable objection stays intact.

Ask whether a named digital fiduciary makes sense. The person best suited to administer a trust is not always the person you’d want reading twenty years of your email or handling a hardware wallet. Some plans benefit from naming a separate digital executor, or from granting narrower digital authority to a co-fiduciary.

Have the plan drafted to work without RUFADAA — and to keep working if it passes. If you are in Massachusetts or Louisiana, ask counsel to draft on the assumption that no statute will supply the defaults, while tracking RUFADAA’s structure closely enough that the documents fit cleanly if your state adopts it.

Reconcile your documents with your online tool designations. Ask your attorney to note in the file who you have named as legacy contact at Apple, Google, and Meta, and to confirm those designations don’t contradict the documents. Remember that the platform designation wins.

Address business digital assets separately. If you own a business, domain registration, payment processor, hosting, social accounts, and administrative logins are business continuity items, not personal estate items. They belong in the succession plan and in your operating agreement, not only in your will.

Next Steps

The reason to do this is not that your digital life is your most valuable asset. It’s that a plan can be beautifully drafted, fully funded, and perfectly current, and still fail at the moment someone needs to log in. That’s a fixable problem, and it’s much easier to fix now than later.

-SM

September 2026 Market Recap: Four Years of Bull

The current bull market in stocks will turn four years old in mid-October.

But the most recent stretch turned from a bull charge in the second quarter of 2026 to a trot in Q3. And September was a plod.

Bull Market Roundup

  • Stock market returns (as measured by the S&P 500 Index of large company U.S. stocks) in the three years following the 2022 bear market were extraordinary: 2023: 26%, 2024: 25%, and 2025: 18%
  • Each of these years was well above the long run annual average return for U.S. stocks of 10%
  • After a pause during the first quarter of 2026, the bull continued to run: the S&P 500 charged ahead by nearly 15% in the April – June period
  • The pace of U.S. large cap stock returns slowed to a modest 2% gain in Q3
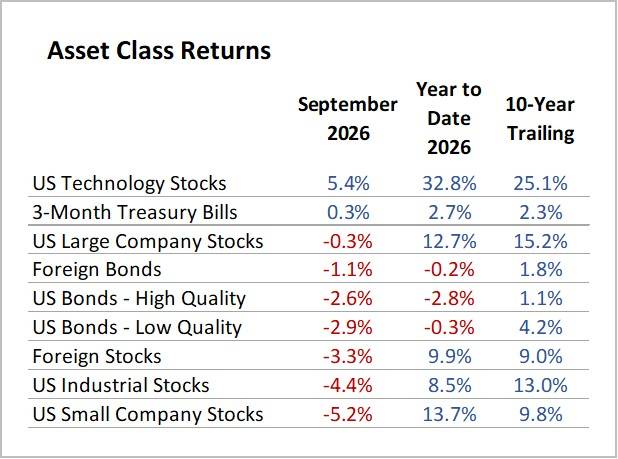
  • In September, positive momentum stalled: while tech stocks pushed higher by 5.4%, most other areas of the market declined – see the details in the chart below

Here are results for September and 2026 Year-to-Date, compared to longer-term annualized returns (10-Year Trailing):

Source: Morningstar

A few of the bigger questions on investors’ minds as we enter the final quarter of 2026 seem to be: What’s worrying the bull? Can the bull keep running in Q4 and beyond? What should investors do now?

The Bull’s Worries

Three issues worrying the bull and raising concerns for investors are:

  1. Oil Prices & Interest Rates: While these are separate items, they are linked. Oil prices have climbed about 50% since the start of the Iran war. Higher oil prices translated directly and immediately to higher prices at the pump for consumers. And when oil stays elevated, the inflation effect broadens out. For example, think about the inflationary impact that higher fertilizer costs have on producing food; or that higher transportation costs (due to elevated diesel prices) have on getting goods to market. Elevated prices triggered the Federal Reserve to act in mid-September. The Fed raised short-term interest rates, and long-term interest rates climbed, too. Higher interest rates mean an increased cost of financing, putting pressure on businesses and consumers alike. Lower profit margins are a headwind for stock prices, and household budget pressures mean potentially less is available for retirement savings and investment. Reduced tension in the Middle East likely would begin to reverse the negative dynamic of elevated energy prices and higher interest rates. Absent progress toward peace, pressure on stocks can persist.
  2. Midterm Elections: In just under a month, the U.S. will hold midterm elections. The midterm year is usually the weakest for the stock market of the four-year presidential cycle. And the stock market swings are typically bigger in midterm years. On average, stocks sink 19% from peak to trough during a midterm year, compared to about 15% on average in non-midterm years. Interestingly, October and November of midterm years have averaged gains of about 3% and 2.7% since 1950. A plausible explanation is that uncertainty drops once the results are known.
  3. Bad Market Breadth: September’s stock price moves show that market returns have narrowed to a relatively small subset of stocks. Last month, almost 80% of stocks in the S&P 500 were down; the average stock was off 5%; and only 2 out of 11 sectors were up, led by technology. Some market commentators call this narrowing of market performance “bad breadth”. Technical analysis Jonathan Krinsky of BTIG, a brokerage firm, was quoted in a recent MarketWatch article, and pointed to bad breadth to support his claim that “the clock is ticking, and we see a sell-off coming sooner than later.”

These issues highlighted above can, and often do, act as a drag on stock prices in the near-term.

But investors should keep these negative influences in perspective.

The direction and rate of change of the U.S. economy tends to have a greater impact on financial markets over the longer term.

The Bull’s Legs

Whether you love it, hate it, or fall somewhere in between, Artificial Intelligence (AI) is giving the stock bull market its legs.

Many of today’s stock market stars are AI-focused companies, because AI usage is increasing rapidly and investors are quite enthusiastic about their future prospects.

But the build-out of AI infrastructure is boosting demand for products and services of all sorts of companies – such as construction firms, industrial manufacturers, power producers, and electric utilities – and is therefore having a much broader impact on the corporate sector and the U.S. economy.

In a recent research note, Capital Group, a California-based fund manager, points out that “the sheer scale of AI-related spending is nothing like we’ve seen before.”

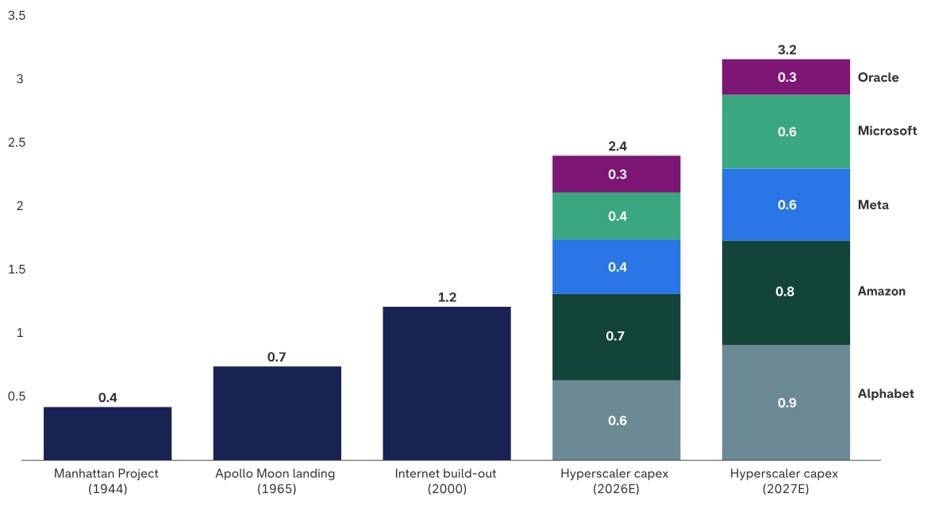
Much of the capital expenditures – an estimated $800 billion in 2026 – are going toward the construction of massive AI data centers and related projects across the U.S. And the spending is expected to accelerate in 2027.

The companies leading the spending charge are well-known technology firms often referred to as “Hyperscalers”: Alphabet, Amazon, Meta Platforms, Microsoft, and Oracle.

The chart below, courtesy of Capital Group, indicates that AI capital expenditure in 2026 will equal 2.4% of U.S. Gross Domestic Product (GDP) in 2026, and rise to 3.2% in 2027. 

Source: Capital Group

This type of spending dwarfs other large, concentrated capital expenditure episodes in history, such as the build out of the internet in 2000 (1.2% of GDP); the Apollo Moon landing in 1965 (0.7% of GDP); and the Manhattan Project in 1944 (0.4% of GDP).

While beyond the scope of this chart, capital expenditure during the railroad buildout in the 1800s was of a similar magnitude as today’s AI activity.

AI spending feeds directly into economic growth. Real U.S. economy is expected to expand by 2.5. – 3.0% (after inflation is considered) in both 2026 and 2027.

Mark Zandi, the chief economist at Moody’s Analytics, estimates that about 30% of the economy’s inflation-adjusted growth this year will come from the AI boom, directly or indirectly (cited in a recent New York Times article).

While stock market selloffs can happen at any time, it would be highly unusual to see an extended stock market downturn or bear market during a time of such strong economic growth.

No Bull: What Investors Should Do

Risk, volatility, and uncertainty often create unease. Discomfort is the price we pay as investors to earn returns that support our financial plans.

The psychological tendency that drives us to do something – even when avoiding action is likely to result in a better outcome – is known as action bias.

Typically, the best course of action is to stay the course, even when the bull market takes a break.

Continuing to make regular contributions to savings and retirement accounts (especially when markets decline), and rebalancing when portfolios get out of line with long-term asset allocation targets, are two of the best moves investors can make.

Beyond this, it can be helpful to meditate on the behavioral mantra that Jack Bogle, the founder of Vanguard, used to implore, especially when investors feel a strong urge to take action in a portfolio because of a perceived negative development (such as, when stocks sell off): “Don’t just do something, sit there!”

Podcast: Trump vs the Bond Market

In keeping with our comment of “fanning the flames of our inner Chicken Little anxieties”, the title of The Ezra Klein Show podcast released on August 28, Trump vs the Bond Market, may well do that.

But unlike many recent articles in the financial press that fall short of providing useful information, this podcast does promote understanding and is worth listening to.

As one might expect from a New York Times sponsored podcast, the journalism is critical of the current administration. But the real value of this episode lies beyond this criticism.

Klein is an astute interviewer and pursues a sincere investigation of today’s US Treasury bond market: what makes it a cornerstone of the global financial system; what’s driving prices and yields; and why it matters.

Guest Robin Wigglesworth is a serious commentator and author. He covers markets and market plumbing closely at Alphaville, a Financial Times (of London) blog, and his books include Trillions (about passive / index investing) and A Fabulous Debt, a history of the bond market, which will be released later this month.

If this month’s article Is the Sky Falling in Bond-land? captured your interest, I’d suggest Klein’s podcast as a way to delve more deeply into what’s happening today in the bond market.

-RK

Early Decision: Is the Admissions Edge Worth the Financial Trade-Off?

If you’ve got a senior at home, chances are the phrase “Early Decision” has already come up at your kitchen table — probably attached to a specific school your child has decided is “the one.” And I get it. There’s something appealing about the idea of being done with the whole admissions ordeal by December instead of April.

But here’s the question I ask every family who brings this up in a planning meeting: are you choosing Early Decision because it’s the right financial move, or because it feels like the fastest way to end the stress?

Those are two very different reasons — and only one of them holds up once real numbers are on the table.

What Early Decision Actually Commits You To

Early Decision (ED) is a binding agreement. Apply, get in, and you’ve committed to attend — full stop. You withdraw every other application, and you show up in the fall.

Most schools run this on one of two timelines:

  • ED I: application deadline in early-to-mid November, decisions typically arrive in mid-December
  • ED II: deadline in early January, decisions in February — a good option for students who didn’t apply ED I or who want a second binding shot at a different school

Early Action (EA), by contrast, gets confused with ED constantly, but it’s a completely different commitment level — EA is non-binding. You get an early answer, but you keep every option (and every financial aid offer) on the table.

Worth double-checking which one your child’s target schools actually offer, because the two get used interchangeably in casual conversation and they are not interchangeable at all.

The Real Trade-Off: Admissions Edge vs. Negotiating Power

Here’s what makes ED genuinely tempting: at most selective schools, Common Data Set filings show ED acceptance rates running two to three times higher than regular decision.

Colleges love ED because it gives them a locked-in yield — no guessing whether an admitted student will actually enroll. In exchange, they’re often more generous with that admissions decision.

But think about what you’re giving up to get that edge. When you apply ED, you commit to attend before you see a single financial aid award. You can’t compare packages. You can’t call a competing school and say, “They offered us more — can you match it?” You’ve taken away your own leverage at the exact moment you’d normally have the most.

For a family paying full freight without blinking, that trade-off is a non-issue. For most families I work with, it’s the whole ball game.

Before Anyone Signs an ED Agreement, Run the Numbers

This is the piece I really want you to take away from this: ED is an admissions tool that works best when you already know, with real confidence, that the school is financially workable for your family. Not hopeful. Confident.

Before your child submits that application, walk through this checklist together:

  • Run the school’s net price calculator with your actual numbers — real income, real assets, not rough estimates. Every school’s NPC lives on its financial aid website, and it takes fifteen minutes.
  • Call the financial aid office directly and ask how they typically treat a family in your income and asset range. Financial aid officers field this question constantly; it’s not an awkward call to make.
  • Confirm whether the school meets 100% of demonstrated need — and if it doesn’t, ask what the gap tends to look like in practice, not just in theory.
  • Have an honest conversation about merit aid. If your child is the kind of applicant who’d likely land significant merit money at a slightly-less-selective school, ED at a need-only school means walking away from that comparison entirely.

In my experience, the families who regret an ED decision are almost never the ones who ran these numbers first and came up short anyway — they’re the ones who skipped the math because the excitement of “getting in” took over the room.

The “Escape Clause” Isn’t the Safety Net You Think It Is

Every ED agreement includes language allowing withdrawal if the financial aid offered makes attendance genuinely impossible. That’s real, and it exists for exactly this reason.

But don’t treat it as a backup plan. The school decides whether your circumstances qualify, and that’s a subjective call made by an institution that has every incentive to see it your way as little as possible.

If you do end up needing it, document your numbers clearly, appeal to the financial aid office first before formally withdrawing, and go in prepared — but don’t apply ED assuming you can quietly opt out later if the number is a little higher than you’d hoped. “A little higher than hoped” almost never clears the bar. “Genuinely cannot pay” sometimes does.

Who Should Think Twice

ED tends to be the riskiest financial decision for a specific group: families in that broad middle-income range (roughly $75,000–$200,000 in household income) who are neither eligible for the most generous need-based aid nor advantaged by a strategy built entirely around merit scholarships elsewhere.

If that’s your household, and your child is choosing between an ED reach school and other options that might offer real merit money, that’s a conversation worth having before November — not after an acceptance letter shows up.

The Bottom Line

Early Decision isn’t wrong. For the right family — one who’s done the math, run the net price calculators, and can comfortably say yes regardless of what the aid letter says — it can genuinely be the smoothest path through senior year. But it should be a financial decision dressed up as an admissions strategy, never the other way around.

If your family is weighing ED for this application cycle, let’s sit down and run your specific numbers before that November deadline arrives. Fifteen minutes with a net price calculator now beats a difficult phone call to a financial aid office in December.

Estate Planning Essentials

If you’ve never sat down and mapped out an estate plan — or if it’s been a while since you last looked at yours — you’re not alone.

Estate planning is one of those tasks that’s easy to keep putting off, partly because it can feel complicated, and partly because it means thinking about things we’d rather not think about.

But a good estate plan doesn’t have to be complicated, and it isn’t just for the ultra-wealthy.

It’s simply a way of making sure your wishes are carried out, your loved ones are protected, and the people you trust have clear authority to act on your behalf if you ever can’t act for yourself.

What Is an Estate Plan, and Why Does It Matter?

At its core, an estate plan is a set of legal documents that spells out two things:

  1. who makes decisions on your behalf if you become unable to make them yourself
  2. who receives your property when you pass away

That’s it. Everything else — trusts, tax strategies, beneficiary designations — exists to support those two goals.

Without a plan, state law fills the gap, and state law doesn’t know your family, your wishes, or your relationships. If you die without a will, state intestacy rules decide who inherits your assets, and the outcome may look nothing like what you intended.

If you become incapacitated without the right documents in place, your family may need to petition a court for guardianship just to pay your bills or make medical decisions — a process that costs time, money, and often adds stress at an already difficult moment.

Put simply: an estate plan isn’t about how much you have. It’s about making sure the people you love aren’t left guessing, or worse, fighting, over decisions you could have made in advance.

The Core Documents Everyone Should Have

A complete estate plan generally rests on four foundational documents:

  • Last Will and Testament: Directs how your property is distributed at death and names an executor to settle your affairs. Importantly, a will does not avoid probate — the court process of validating a will and overseeing the distribution of assets.
  • Durable Financial Power of Attorney: Names someone to handle financial matters on your behalf (paying bills, managing accounts, filing taxes) if you’re unable to.
  • Health Care Power of Attorney: Names someone to make medical decisions for you if you can’t communicate your own wishes.
  • Living Will: Documents your preferences for life-sustaining treatment (resuscitation, artificial nutrition, ventilation, etc.) if you’re terminally ill and incapacitated.

These four documents cover the essentials for nearly everyone. A trust is a common — and often valuable — addition, but it’s not a requirement for a complete plan. We’ll get into why you might (or might not) want one next.

What Is a Trust, and Why Consider One?

A trust is a legal arrangement in which one party (the trustee) holds and manages property for the benefit of another (the beneficiary), according to instructions the person creating the trust (the grantor) has laid out.

The most common version — a revocable living trust — is created while you’re alive and can be changed or revoked at any time.

The main appeal of a revocable living trust is that assets held in it bypass probate entirely. That means a faster, more private transfer of assets to your heirs, without the court filings and public record that come with probate.

Trusts can also give you more control — for example, spelling out that a beneficiary receives distributions in stages rather than all at once, which can be valuable if you’re providing for a minor, a beneficiary who struggles with money management, or a blended family with competing interests.

That said, a trust isn’t automatically necessary for everyone. If your goals can be met through straightforward beneficiary designations, joint ownership, and transfer-on-death titling, a trust may add cost and complexity without adding much benefit.

It’s worth weighing your specific situation — family structure, asset types, and privacy or control preferences — before deciding.

For those who do have a need, a few purpose-built trusts come up often, particularly for couples and larger estates:

  • Marital (“A”) and Bypass (“B”) Trusts — Used together by married couples to make full use of both spouses’ estate tax exemptions while still providing for a surviving spouse.
  • Spousal Lifetime Access Trust (SLAT) — Removes assets from one spouse’s taxable estate while still allowing the other spouse access to the trust for support.
  • Irrevocable Life Insurance Trust (ILIT) — Holds a life insurance policy outside your taxable estate, while still providing liquidity to your beneficiaries.
  • Special Needs Trust (SNT) — Provides for a beneficiary with a disability without disqualifying them from means-tested government benefits.

These are more specialized tools, and whether any of them make sense depends on the size of your estate, your family circumstances, and your goals — not something to adopt off a checklist.

Putting It Together: A Snapshot of a Comprehensive Estate Plan

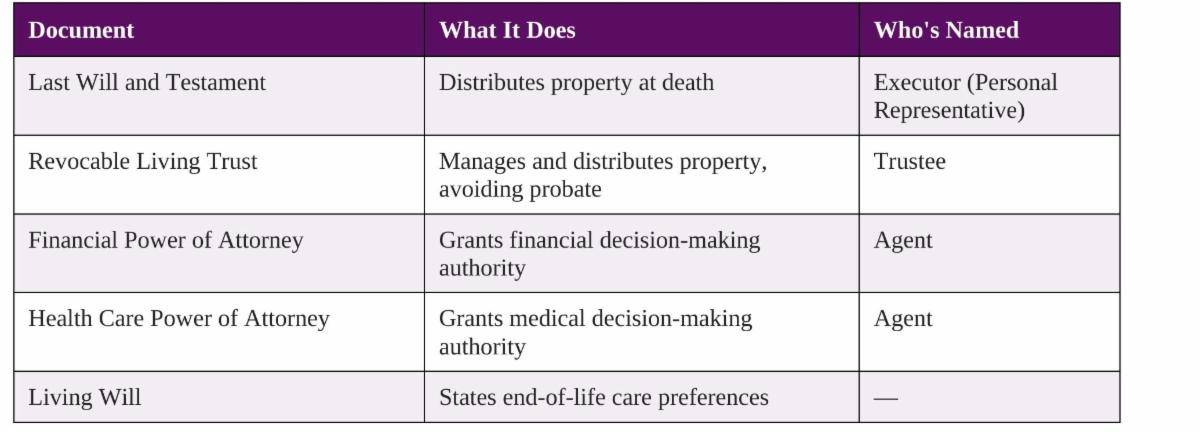
Here’s how the pieces above typically fit together, along with the key people involved in carrying them out:

Source: Moore Financial Advisors

And a few of the people who carry out these documents:

  • Executor — Settles the estate as directed by the will (probate, debts, final taxes, distributions)
  • Trustee — Manages trust assets and carries out the trust’s instructions for beneficiaries
  • Agent (Power of Attorney) — Makes financial and/or medical decisions on your behalf
  • Guardian — Cares for minor children, typically named in the will

A note on terminology: you’ll often see the term Personal Representative used alongside — or in place of — “Executor.”

Personal Representative is the broader, more modern legal term for the person who administers an estate under the court’s supervision; many states, including Massachusetts, now use it as the official title in place of “Executor.”

In everyday conversation, the two terms are generally used interchangeably, and you may see either one depending on which state’s forms or statutes are being referenced.

Seeing it laid out this way helps clarify a point worth repeating: these documents work as a system. A gap in one (say, an outdated will or a trust that was never funded) can undercut the whole plan.

How a Will and a Trust Work Together

If you have both a will and a trust, it’s important to understand how they interact. A trust only avoids probate for assets that have actually been retitled, or “funded,” into it — a trust that owns nothing accomplishes nothing.

Because it’s common for a few assets to be missed along the way, most trust-based plans also include a pour-over will, which directs any assets left in your individual name at death into the trust. Those “poured over” assets still pass through probate, but the pour-over will acts as a safety net to make sure nothing falls outside the plan entirely.

Even with a fully funded trust, you still need a will. Wills handle things a trust doesn’t: naming guardians for minor children, addressing personal property not held in the trust, and serving as the final backstop for anything unaccounted for.

Why Reviewing Beneficiaries Matters

Here’s a detail that surprises many people: beneficiary designations on accounts like retirement plans, life insurance, and annuities override what your will or trust says. If your 401(k) still lists an ex-spouse, or your IRA names your estate instead of a person, that’s what governs — regardless of your other planning documents.

A few things worth checking periodically:

  • Do your named beneficiaries reflect your current wishes and family situation?
  • Have you listed your “estate” as a beneficiary anywhere? (This forces those assets through probate)
  • Are any beneficiaries minors? (Minors generally can’t inherit directly, which can trigger a court-appointed conservatorship)
  • If a trust is named as beneficiary, is that trust still current and appropriate?
  • A quick beneficiary review takes a few minutes and can prevent outcomes no one intended

How Often Should You Update Your Estate Plan?

There’s no fixed schedule that fits everyone, but two categories of events should prompt a review:

  • Life events: marriage, divorce, births, the death of a named executor, trustee, or agent, a move to a new state, or a significant change in your assets.
  • Law changes: federal and state estate tax rules shift periodically. As of 2026, the federal estate and gift tax exemption increased to $15 million per individual ($30 million for married couples) — a change that affects very few households directly. Massachusetts is a different story: the state estate tax exemption remains $2 million per person, and unlike the federal exemption, it is not portable between spouses.

For many Massachusetts homeowners, home equity and retirement accounts alone can approach that threshold — which is exactly the kind of gap a periodic review is meant to catch.

As a general rule of thumb, a full review every three to five years — or immediately after any major life event — is a reasonable cadence.

Why Use an Estate Planning Attorney — and Is It Worth the Cost?

It’s tempting to reach for an online template to save money, and for very simple situations that may work. But an estate planning attorney brings a few things a template can’t:

  • State-specific compliance. Estate law varies significantly by state, and a document valid in one state may not hold up in another
  • Tailored drafting. Your family situation, assets, and goals are unique; a generic template can’t anticipate the details that matter for your plan
  • Coordination. An attorney ensures your will, trust, and powers of attorney work together rather than contradicting each other
  • Accountability. Attorneys carry malpractice coverage and professional responsibility that a downloaded form does not

The cost of hiring an attorney is real, but it’s worth weighing against the alternative: a contested or invalid will, a costly and public probate process, or family conflict that a properly drafted plan could have prevented. For most families, the upfront cost of good legal work is modest compared to what’s at stake.

This is general education, not a recommendation for your specific situation — if you don’t already have a trusted estate planning attorney, we’re glad to make an introduction.

What Role Does a Financial Advisor Play in Estate Planning?

Our role is to work alongside your attorney and tax preparer, not in place of them. In practice, that means:

  • Making sure beneficiary designations on your investment and retirement accounts match your overall estate planning intentions
  • Reviewing how assets are titled (individually, jointly, or in trust) to ensure alignment with your plan
  • Keeping an eye on how life changes or new laws might affect your existing plan, and flagging when it may be time to revisit it with your attorney

We’re not attorneys, and we don’t draft legal documents or give legal advice — but we do help make sure the financial side of your plan supports the legal side.

-RK

Is the Sky Falling in Bond-Land?

A common perception of the bond market is that it is a puzzling and uninteresting place. Even so, recent articles in the financial press may have grabbed your attention and might have given you the impression that the sky is falling in bond-land.

Here’s a sample of headlines focused on the bond market from the past few weeks:

  • Global Bond Selloff Sends Yields to Highest Since 2008 – Bloomberg
  • Why the Global Bond Yield Crisis Is Just Getting Started – Barron’s
  • Europe’s Bond Markets Are Suffering a Post-Holiday Shock – The Economist
  • The Treasury Market’s Coveted Status as a Safe Haven is Fading – The Wall Street Journal
  • The National Debt Is Wreaking Havoc with Bonds – Barron’s

Using terms like “crisis”, “shock”, and “wreaking havoc” may grab attention and fan the flames of our inner Chicken Little anxieties.

But this type of language and financial journalism falls short of providing useful information and promoting understanding.

To address concerns related to the bond market, we’ll go through some bond market basics; address current issues affecting bond yields and prices; and explain why a bond allocation is and will continue to be an important component of most well-diversified portfolios.

Bond Market Basics

To many individual investors, stocks are straightforward.

Buying a piece of a company that we know, and being able to track the share price, connects us to our stock investment. If good things happen to the company, the share price typically goes up. And if a company’s fortunes fall, so does the stock.

Bonds, however, are much less familiar. So here are some things to know:

The US bond market, at about $58 trillion in market value, is approximately the size of the US stock market.

But the bond market is arguably more consequential to the real economy than the stock market for a few reasons:

  • Funding Costs: It’s how governments and companies fund themselves. Bonds are tradable loans. When governments and companies issue bonds, they receive cash and promise to pay interest to the bond buyer for the use of that cash. The issuer also promises to return the principal to the bondholder when the bond matures.
  • Risk-Free Rate: The Treasury bond yield establishes the “risk-free rate” that many financial instruments are priced against – mortgage rates, corporate borrowing cost, and even stock valuations (via discount rates) all trace back to Treasury yields.
  • Economic Barometer: Institutional bond investors and Wall Street traders are constantly considering inflation, economic growth, and Federal Reserve interest rate policies when deciding what price and yield to accept when they buy and sell bonds. Shifts in bond yields often signal changing expectations before they show up elsewhere.
  • Big Money: the more risk-averse, large pools of capital, such as pension funds, insurers, central banks, and foreign governments, are major holders of bonds, so instability in the bond market ripples through the global financial system in a way that declines in US stocks often don’t.

When talking about the situation in the bond market, the discussion usually centers around bond yields. A bond yield is the annual return an investor earns for holding a bond, and the yield moves inversely to the bond’s price.

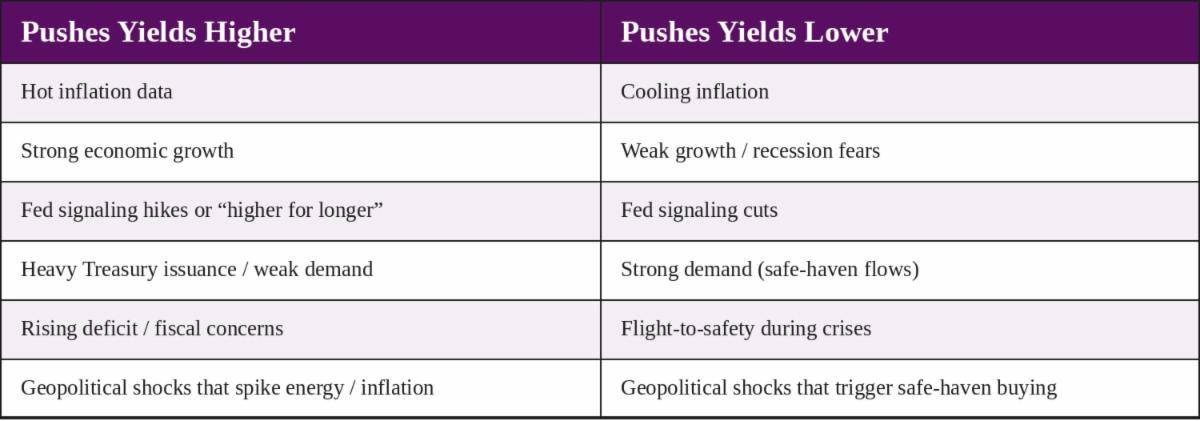
The table below presents some factors that influence the direction of Treasury bond yields.

Source: Moore Financial Advisors

Bond Market Current Issues

It is a fact that yields have pushed higher in the US, as well as in other countries, this year.

From a low point of 3.9% in early January 10-Year Treasury yields climbed nearly a percentage point, to 4.78% in early September.

Short-term Treasury Bond and Bill yields are also up by about a percentage point and currently sit at about 4.0%.

It’s also true that for many investors, returns for high quality intermediate and long-term bond funds have fallen short of expectations in 2026.

The benchmark US Bloomberg Aggregate Bond Index, which is made up of thousands of high-quality issues, including US Treasuries, guaranteed mortgage-backed securities, and corporate bonds, has produced a negative return of -0.25% year-to-date as of September 4.

Financial markets experts point to several factors behind the increase in yields, including:

  • investors’ concerns that inflation is too high
  • central banks around the world aren’t doing enough to contain inflation
  • governments are acting in fiscally irresponsible ways by running large, successive deficits – particularly since the pandemic

These are valid concerns and could lead to more upward pressure on bond yields in the future, but do not point to imminent crisis.

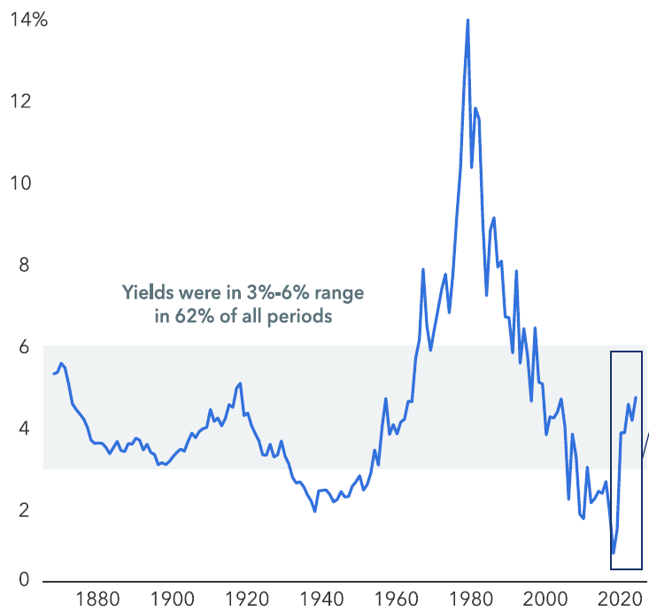
Courtesy of Capital Group, the chart below shows a 155-year history of long-term Treasury bond yields going back to 1871. 

Source: Capital Group

Prior to 1962, the data represents the average long-term government bond yield; from 1962 forward, the data represents 10-Year Treasury yields as of December 31 each year within the period.

The data shows that 62% of the time, long-term Treasury bond yields fall within a range of 3% to 6%.

When bond yields move out of this range, it’s a strong possibility that something may be amiss in the economy or the financial markets.

In the 1970s and 1980s, the US economy was stressed by energy shocks, rolling recessions, and elevated inflation, which pushed interest rates well above the normal band to record high levels.

In the 15 years following 2006, the US economy was challenged by fallout from a global financial crisis (2008-2009) and a pandemic (2020) which pulled interest rates well below the normal band to record low levels.

Today’s interest rates, when viewed through a long-term historical lens, sit comfortably in the middle of the normal band.

According to analysis done by JP Morgan asset management, 10-year Treasury yields have averaged 5.7% since 1958. A 10-year yield approaching 4.8% is hardly indicative of “crisis”, “shock”, or “havoc”.

To some extent, modestly higher yields can be considered good news for bondholders.

With stock markets at record highs, the rise in yields reflects a resilient global economy that can absorb higher borrowing costs. And higher yields mean investing in bonds today will deliver more income over time.

Why Hold Bonds in Your Portfolio?

Even though the environment for bond investors has been challenging for most of 2026, the main reasons for owning high-quality bonds, including US Treasuries, remain intact:

  • Bonds provide recurring, dependable income
  • Investment-grade bonds with near- to intermediate-term maturities are less volatile than stocks, and can help stabilize a portfolio when financial markets become unsettled
  • Shorter-maturity bonds and bond funds are typically a good source of “liquidity” and convert easily to cash when money must be withdrawn from a portfolio

The bottom line: the sky is not falling in bond-land.

The unsatisfactory returns many investors have experienced in their bond allocations year to date likely have been counterbalanced by satisfactory returns from their stock allocations.

Also, sub-par bond returns this year are coming on the heels of above-average returns for bonds last year.

This return experience is normal and indicative of a generally healthy economic and financial market environment.

For most individual investors, an allocation to bonds is, and will continue to be, an important component of a well-diversified portfolio.

-RK

August 2026 Market Recap:

This month’s financial market commentary has been kept purposefully brief. We’ve provided a separate article entitled Is the Sky Falling in Bond-land? that goes into more depth about developments in the bond market. (You will see that article in our next blog post.)

Resilient corporate earnings were the main development that supported the stock market in August.

Earnings reports for the second quarter ended June 30 in aggregate turned out to be much better than anticipated and far better than last year.

For example, Nvidia, the maker of chips used in AI data centers (and currently the largest company in the US when measured by stock market value) announced stellar results in late August.

But what really caught the attention of investors was Nvidia’s forecast that strong sales growth would continue well into next year.

With most large, publicly traded companies having released their results for second quarter, 76% exceeded analysts’ expectations.

Sales in the second quarter of 2026 were up 15% compared to the same period last year, and earnings were up by 32%.

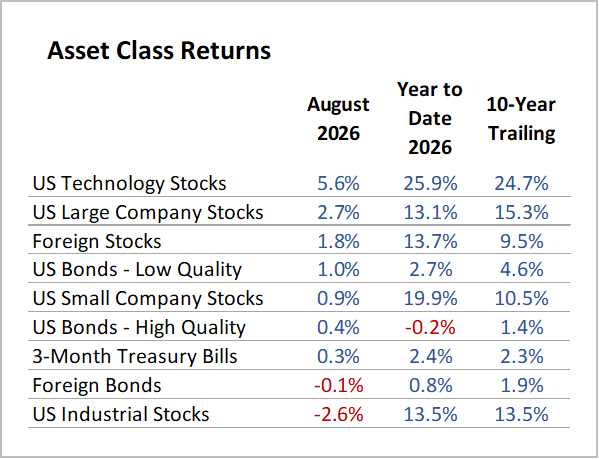
The month of August was generally positive for both stocks and bonds, reversing the weak performance experienced by most market segments in July.

US Technology stocks led the way with a 5.6% increase. Large company US stocks did well, rising by 2.7%, and foreign company stocks weren’t far behind, with an increase of 1.8%. Small company US stocks struggled to keep pace but still generated positive performance of 0.9%.

Gains in the US bond market were more muted, but still generally positive, with high-quality bonds returning 0.4%, and US Treasury bills up 0.3%. Foreign bonds were the laggard, declining by a modest 0.1%.

Here are results for August and 2026 Year-to-Date, compared to longer-term annualized returns (10-Year Trailing):

Source: Morningstar

-RK

Kings

We’re now at peak summer season, and I hope you’re finding time to rest, relax, and enjoy some reading that takes you farther afield. Here are two non-finance books that I’ve enjoyed this summer.

King of Kings: The Iranian Revolution: A Story of Hubris, Delusion and Catastrophic Miscalculation by Scott Anderson

I trace my first recollection of political awareness back to 1979. In 5th grade, one student stood out as more worldly than the rest of us. She talked about the Middle East, oil, political strife, the State Department, and “the Shah” – things I knew nothing about at the time.

I’d filled in some of the gaps since then, but Anderson’s book tells a full story of what happened in Iran in the late 1970s.

Once toasted by President Carter as an unshakable ally presiding over “an island of stability,” commanding the world’s fifth largest army and vast oil wealth— Shah Mohammad Reza Pahlavi fled into exile just fourteen months later, forced out by a religious revolution led by Ayatollah Khomeini.

Anderson frames the collapse as a story of American diplomatic blunders and miscalculations that helped trigger hostilities that have destabilized the region for decades, arguing that the revolution was as world-shattering as the French and Russian revolutions.

What makes it especially resonant now is the broader pattern Anderson identifies: the resentment of economically marginalized, religiously fervent populations toward a wealthy secular elite has fueled unrest across the Middle East, India, Southeast Asia, and Europe – with Iran serving as the template.

The book is a useful lens for understanding how great-power miscalculation and populist backlash can compound into events with generational consequences.


Monsters in the Archives: My Year of Fear with Stephen King by Caroline Bicks

My summer wouldn’t be complete without reading something by, or about, Stephen King.

A few months ago, I was listening to a BBC reporter interview Caroline Bicks, the inaugural Stephen E. King Chair of Literature at the University of Maine.

Bicks told the story that she was instructed by the University of Maine administration to set aside the idea of ever getting in touch with Stephen King, despite her holding the chair endowed by him.

However, King eventually reached out to Bicks, they struck up a professional relationship and friendship, and this book is the product of her having access to his archives.

Monsters in the Archives is part literary master class, part biography, part memoir, and an investigation into our deepest anxieties, drawing on unprecedented access to King’s private papers.

Bicks focuses on five of King’s most iconic early works—The Shining, Carrie, Pet Sematary, ‘Salem’s Lot, and Night Shift—tracing his margin notes and editorial changes to reveal how he built his language, storylines, and characters, and she uncovered unpublished scenes and alternate endings that King allowed her to publish for the first time.

The book offers longtime readers a rare backstage look at how some of the most influential horror fiction of the last half-century was actually constructed, alongside Bicks’s own story of rereading these books as an adult confronting the childhood fears they first stirred in her.

Happy Reading!

-RK