Monthly Archives

September 2026

Podcast: Trump vs the Bond Market

In keeping with our comment of “fanning the flames of our inner Chicken Little anxieties”, the title of The Ezra Klein Show podcast released on August 28, Trump vs the Bond Market, may well do that.

But unlike many recent articles in the financial press that fall short of providing useful information, this podcast does promote understanding and is worth listening to.

As one might expect from a New York Times sponsored podcast, the journalism is critical of the current administration. But the real value of this episode lies beyond this criticism.

Klein is an astute interviewer and pursues a sincere investigation of today’s US Treasury bond market: what makes it a cornerstone of the global financial system; what’s driving prices and yields; and why it matters.

Guest Robin Wigglesworth is a serious commentator and author. He covers markets and market plumbing closely at Alphaville, a Financial Times (of London) blog, and his books include Trillions (about passive / index investing) and A Fabulous Debt, a history of the bond market, which will be released later this month.

If this month’s article Is the Sky Falling in Bond-land? captured your interest, I’d suggest Klein’s podcast as a way to delve more deeply into what’s happening today in the bond market.

-RK

Early Decision: Is the Admissions Edge Worth the Financial Trade-Off?

If you’ve got a senior at home, chances are the phrase “Early Decision” has already come up at your kitchen table — probably attached to a specific school your child has decided is “the one.” And I get it. There’s something appealing about the idea of being done with the whole admissions ordeal by December instead of April.

But here’s the question I ask every family who brings this up in a planning meeting: are you choosing Early Decision because it’s the right financial move, or because it feels like the fastest way to end the stress?

Those are two very different reasons — and only one of them holds up once real numbers are on the table.

What Early Decision Actually Commits You To

Early Decision (ED) is a binding agreement. Apply, get in, and you’ve committed to attend — full stop. You withdraw every other application, and you show up in the fall.

Most schools run this on one of two timelines:

  • ED I: application deadline in early-to-mid November, decisions typically arrive in mid-December
  • ED II: deadline in early January, decisions in February — a good option for students who didn’t apply ED I or who want a second binding shot at a different school

Early Action (EA), by contrast, gets confused with ED constantly, but it’s a completely different commitment level — EA is non-binding. You get an early answer, but you keep every option (and every financial aid offer) on the table.

Worth double-checking which one your child’s target schools actually offer, because the two get used interchangeably in casual conversation and they are not interchangeable at all.

The Real Trade-Off: Admissions Edge vs. Negotiating Power

Here’s what makes ED genuinely tempting: at most selective schools, Common Data Set filings show ED acceptance rates running two to three times higher than regular decision.

Colleges love ED because it gives them a locked-in yield — no guessing whether an admitted student will actually enroll. In exchange, they’re often more generous with that admissions decision.

But think about what you’re giving up to get that edge. When you apply ED, you commit to attend before you see a single financial aid award. You can’t compare packages. You can’t call a competing school and say, “They offered us more — can you match it?” You’ve taken away your own leverage at the exact moment you’d normally have the most.

For a family paying full freight without blinking, that trade-off is a non-issue. For most families I work with, it’s the whole ball game.

Before Anyone Signs an ED Agreement, Run the Numbers

This is the piece I really want you to take away from this: ED is an admissions tool that works best when you already know, with real confidence, that the school is financially workable for your family. Not hopeful. Confident.

Before your child submits that application, walk through this checklist together:

  • Run the school’s net price calculator with your actual numbers — real income, real assets, not rough estimates. Every school’s NPC lives on its financial aid website, and it takes fifteen minutes.
  • Call the financial aid office directly and ask how they typically treat a family in your income and asset range. Financial aid officers field this question constantly; it’s not an awkward call to make.
  • Confirm whether the school meets 100% of demonstrated need — and if it doesn’t, ask what the gap tends to look like in practice, not just in theory.
  • Have an honest conversation about merit aid. If your child is the kind of applicant who’d likely land significant merit money at a slightly-less-selective school, ED at a need-only school means walking away from that comparison entirely.

In my experience, the families who regret an ED decision are almost never the ones who ran these numbers first and came up short anyway — they’re the ones who skipped the math because the excitement of “getting in” took over the room.

The “Escape Clause” Isn’t the Safety Net You Think It Is

Every ED agreement includes language allowing withdrawal if the financial aid offered makes attendance genuinely impossible. That’s real, and it exists for exactly this reason.

But don’t treat it as a backup plan. The school decides whether your circumstances qualify, and that’s a subjective call made by an institution that has every incentive to see it your way as little as possible.

If you do end up needing it, document your numbers clearly, appeal to the financial aid office first before formally withdrawing, and go in prepared — but don’t apply ED assuming you can quietly opt out later if the number is a little higher than you’d hoped. “A little higher than hoped” almost never clears the bar. “Genuinely cannot pay” sometimes does.

Who Should Think Twice

ED tends to be the riskiest financial decision for a specific group: families in that broad middle-income range (roughly $75,000–$200,000 in household income) who are neither eligible for the most generous need-based aid nor advantaged by a strategy built entirely around merit scholarships elsewhere.

If that’s your household, and your child is choosing between an ED reach school and other options that might offer real merit money, that’s a conversation worth having before November — not after an acceptance letter shows up.

The Bottom Line

Early Decision isn’t wrong. For the right family — one who’s done the math, run the net price calculators, and can comfortably say yes regardless of what the aid letter says — it can genuinely be the smoothest path through senior year. But it should be a financial decision dressed up as an admissions strategy, never the other way around.

If your family is weighing ED for this application cycle, let’s sit down and run your specific numbers before that November deadline arrives. Fifteen minutes with a net price calculator now beats a difficult phone call to a financial aid office in December.

Estate Planning Essentials

If you’ve never sat down and mapped out an estate plan — or if it’s been a while since you last looked at yours — you’re not alone.

Estate planning is one of those tasks that’s easy to keep putting off, partly because it can feel complicated, and partly because it means thinking about things we’d rather not think about.

But a good estate plan doesn’t have to be complicated, and it isn’t just for the ultra-wealthy.

It’s simply a way of making sure your wishes are carried out, your loved ones are protected, and the people you trust have clear authority to act on your behalf if you ever can’t act for yourself.

What Is an Estate Plan, and Why Does It Matter?

At its core, an estate plan is a set of legal documents that spells out two things:

  1. who makes decisions on your behalf if you become unable to make them yourself
  2. who receives your property when you pass away

That’s it. Everything else — trusts, tax strategies, beneficiary designations — exists to support those two goals.

Without a plan, state law fills the gap, and state law doesn’t know your family, your wishes, or your relationships. If you die without a will, state intestacy rules decide who inherits your assets, and the outcome may look nothing like what you intended.

If you become incapacitated without the right documents in place, your family may need to petition a court for guardianship just to pay your bills or make medical decisions — a process that costs time, money, and often adds stress at an already difficult moment.

Put simply: an estate plan isn’t about how much you have. It’s about making sure the people you love aren’t left guessing, or worse, fighting, over decisions you could have made in advance.

The Core Documents Everyone Should Have

A complete estate plan generally rests on four foundational documents:

  • Last Will and Testament: Directs how your property is distributed at death and names an executor to settle your affairs. Importantly, a will does not avoid probate — the court process of validating a will and overseeing the distribution of assets.
  • Durable Financial Power of Attorney: Names someone to handle financial matters on your behalf (paying bills, managing accounts, filing taxes) if you’re unable to.
  • Health Care Power of Attorney: Names someone to make medical decisions for you if you can’t communicate your own wishes.
  • Living Will: Documents your preferences for life-sustaining treatment (resuscitation, artificial nutrition, ventilation, etc.) if you’re terminally ill and incapacitated.

These four documents cover the essentials for nearly everyone. A trust is a common — and often valuable — addition, but it’s not a requirement for a complete plan. We’ll get into why you might (or might not) want one next.

What Is a Trust, and Why Consider One?

A trust is a legal arrangement in which one party (the trustee) holds and manages property for the benefit of another (the beneficiary), according to instructions the person creating the trust (the grantor) has laid out.

The most common version — a revocable living trust — is created while you’re alive and can be changed or revoked at any time.

The main appeal of a revocable living trust is that assets held in it bypass probate entirely. That means a faster, more private transfer of assets to your heirs, without the court filings and public record that come with probate.

Trusts can also give you more control — for example, spelling out that a beneficiary receives distributions in stages rather than all at once, which can be valuable if you’re providing for a minor, a beneficiary who struggles with money management, or a blended family with competing interests.

That said, a trust isn’t automatically necessary for everyone. If your goals can be met through straightforward beneficiary designations, joint ownership, and transfer-on-death titling, a trust may add cost and complexity without adding much benefit.

It’s worth weighing your specific situation — family structure, asset types, and privacy or control preferences — before deciding.

For those who do have a need, a few purpose-built trusts come up often, particularly for couples and larger estates:

  • Marital (“A”) and Bypass (“B”) Trusts — Used together by married couples to make full use of both spouses’ estate tax exemptions while still providing for a surviving spouse.
  • Spousal Lifetime Access Trust (SLAT) — Removes assets from one spouse’s taxable estate while still allowing the other spouse access to the trust for support.
  • Irrevocable Life Insurance Trust (ILIT) — Holds a life insurance policy outside your taxable estate, while still providing liquidity to your beneficiaries.
  • Special Needs Trust (SNT) — Provides for a beneficiary with a disability without disqualifying them from means-tested government benefits.

These are more specialized tools, and whether any of them make sense depends on the size of your estate, your family circumstances, and your goals — not something to adopt off a checklist.

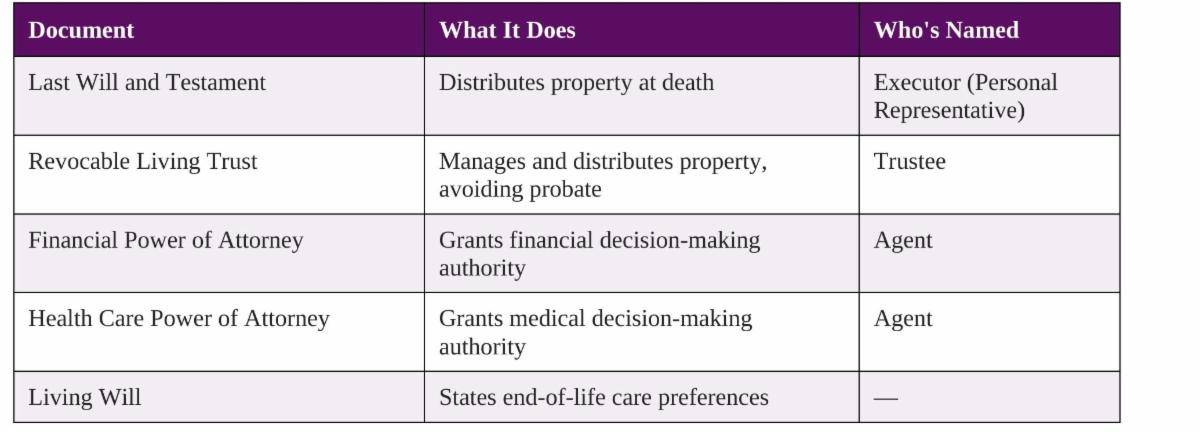
Putting It Together: A Snapshot of a Comprehensive Estate Plan

Here’s how the pieces above typically fit together, along with the key people involved in carrying them out:

Source: Moore Financial Advisors

And a few of the people who carry out these documents:

  • Executor — Settles the estate as directed by the will (probate, debts, final taxes, distributions)
  • Trustee — Manages trust assets and carries out the trust’s instructions for beneficiaries
  • Agent (Power of Attorney) — Makes financial and/or medical decisions on your behalf
  • Guardian — Cares for minor children, typically named in the will

A note on terminology: you’ll often see the term Personal Representative used alongside — or in place of — “Executor.”

Personal Representative is the broader, more modern legal term for the person who administers an estate under the court’s supervision; many states, including Massachusetts, now use it as the official title in place of “Executor.”

In everyday conversation, the two terms are generally used interchangeably, and you may see either one depending on which state’s forms or statutes are being referenced.

Seeing it laid out this way helps clarify a point worth repeating: these documents work as a system. A gap in one (say, an outdated will or a trust that was never funded) can undercut the whole plan.

How a Will and a Trust Work Together

If you have both a will and a trust, it’s important to understand how they interact. A trust only avoids probate for assets that have actually been retitled, or “funded,” into it — a trust that owns nothing accomplishes nothing.

Because it’s common for a few assets to be missed along the way, most trust-based plans also include a pour-over will, which directs any assets left in your individual name at death into the trust. Those “poured over” assets still pass through probate, but the pour-over will acts as a safety net to make sure nothing falls outside the plan entirely.

Even with a fully funded trust, you still need a will. Wills handle things a trust doesn’t: naming guardians for minor children, addressing personal property not held in the trust, and serving as the final backstop for anything unaccounted for.

Why Reviewing Beneficiaries Matters

Here’s a detail that surprises many people: beneficiary designations on accounts like retirement plans, life insurance, and annuities override what your will or trust says. If your 401(k) still lists an ex-spouse, or your IRA names your estate instead of a person, that’s what governs — regardless of your other planning documents.

A few things worth checking periodically:

  • Do your named beneficiaries reflect your current wishes and family situation?
  • Have you listed your “estate” as a beneficiary anywhere? (This forces those assets through probate)
  • Are any beneficiaries minors? (Minors generally can’t inherit directly, which can trigger a court-appointed conservatorship)
  • If a trust is named as beneficiary, is that trust still current and appropriate?
  • A quick beneficiary review takes a few minutes and can prevent outcomes no one intended

How Often Should You Update Your Estate Plan?

There’s no fixed schedule that fits everyone, but two categories of events should prompt a review:

  • Life events: marriage, divorce, births, the death of a named executor, trustee, or agent, a move to a new state, or a significant change in your assets.
  • Law changes: federal and state estate tax rules shift periodically. As of 2026, the federal estate and gift tax exemption increased to $15 million per individual ($30 million for married couples) — a change that affects very few households directly. Massachusetts is a different story: the state estate tax exemption remains $2 million per person, and unlike the federal exemption, it is not portable between spouses.

For many Massachusetts homeowners, home equity and retirement accounts alone can approach that threshold — which is exactly the kind of gap a periodic review is meant to catch.

As a general rule of thumb, a full review every three to five years — or immediately after any major life event — is a reasonable cadence.

Why Use an Estate Planning Attorney — and Is It Worth the Cost?

It’s tempting to reach for an online template to save money, and for very simple situations that may work. But an estate planning attorney brings a few things a template can’t:

  • State-specific compliance. Estate law varies significantly by state, and a document valid in one state may not hold up in another
  • Tailored drafting. Your family situation, assets, and goals are unique; a generic template can’t anticipate the details that matter for your plan
  • Coordination. An attorney ensures your will, trust, and powers of attorney work together rather than contradicting each other
  • Accountability. Attorneys carry malpractice coverage and professional responsibility that a downloaded form does not

The cost of hiring an attorney is real, but it’s worth weighing against the alternative: a contested or invalid will, a costly and public probate process, or family conflict that a properly drafted plan could have prevented. For most families, the upfront cost of good legal work is modest compared to what’s at stake.

This is general education, not a recommendation for your specific situation — if you don’t already have a trusted estate planning attorney, we’re glad to make an introduction.

What Role Does a Financial Advisor Play in Estate Planning?

Our role is to work alongside your attorney and tax preparer, not in place of them. In practice, that means:

  • Making sure beneficiary designations on your investment and retirement accounts match your overall estate planning intentions
  • Reviewing how assets are titled (individually, jointly, or in trust) to ensure alignment with your plan
  • Keeping an eye on how life changes or new laws might affect your existing plan, and flagging when it may be time to revisit it with your attorney

We’re not attorneys, and we don’t draft legal documents or give legal advice — but we do help make sure the financial side of your plan supports the legal side.

-RK

Is the Sky Falling in Bond-Land?

A common perception of the bond market is that it is a puzzling and uninteresting place. Even so, recent articles in the financial press may have grabbed your attention and might have given you the impression that the sky is falling in bond-land.

Here’s a sample of headlines focused on the bond market from the past few weeks:

  • Global Bond Selloff Sends Yields to Highest Since 2008 – Bloomberg
  • Why the Global Bond Yield Crisis Is Just Getting Started – Barron’s
  • Europe’s Bond Markets Are Suffering a Post-Holiday Shock – The Economist
  • The Treasury Market’s Coveted Status as a Safe Haven is Fading – The Wall Street Journal
  • The National Debt Is Wreaking Havoc with Bonds – Barron’s

Using terms like “crisis”, “shock”, and “wreaking havoc” may grab attention and fan the flames of our inner Chicken Little anxieties.

But this type of language and financial journalism falls short of providing useful information and promoting understanding.

To address concerns related to the bond market, we’ll go through some bond market basics; address current issues affecting bond yields and prices; and explain why a bond allocation is and will continue to be an important component of most well-diversified portfolios.

Bond Market Basics

To many individual investors, stocks are straightforward.

Buying a piece of a company that we know, and being able to track the share price, connects us to our stock investment. If good things happen to the company, the share price typically goes up. And if a company’s fortunes fall, so does the stock.

Bonds, however, are much less familiar. So here are some things to know:

The US bond market, at about $58 trillion in market value, is approximately the size of the US stock market.

But the bond market is arguably more consequential to the real economy than the stock market for a few reasons:

  • Funding Costs: It’s how governments and companies fund themselves. Bonds are tradable loans. When governments and companies issue bonds, they receive cash and promise to pay interest to the bond buyer for the use of that cash. The issuer also promises to return the principal to the bondholder when the bond matures.
  • Risk-Free Rate: The Treasury bond yield establishes the “risk-free rate” that many financial instruments are priced against – mortgage rates, corporate borrowing cost, and even stock valuations (via discount rates) all trace back to Treasury yields.
  • Economic Barometer: Institutional bond investors and Wall Street traders are constantly considering inflation, economic growth, and Federal Reserve interest rate policies when deciding what price and yield to accept when they buy and sell bonds. Shifts in bond yields often signal changing expectations before they show up elsewhere.
  • Big Money: the more risk-averse, large pools of capital, such as pension funds, insurers, central banks, and foreign governments, are major holders of bonds, so instability in the bond market ripples through the global financial system in a way that declines in US stocks often don’t.

When talking about the situation in the bond market, the discussion usually centers around bond yields. A bond yield is the annual return an investor earns for holding a bond, and the yield moves inversely to the bond’s price.

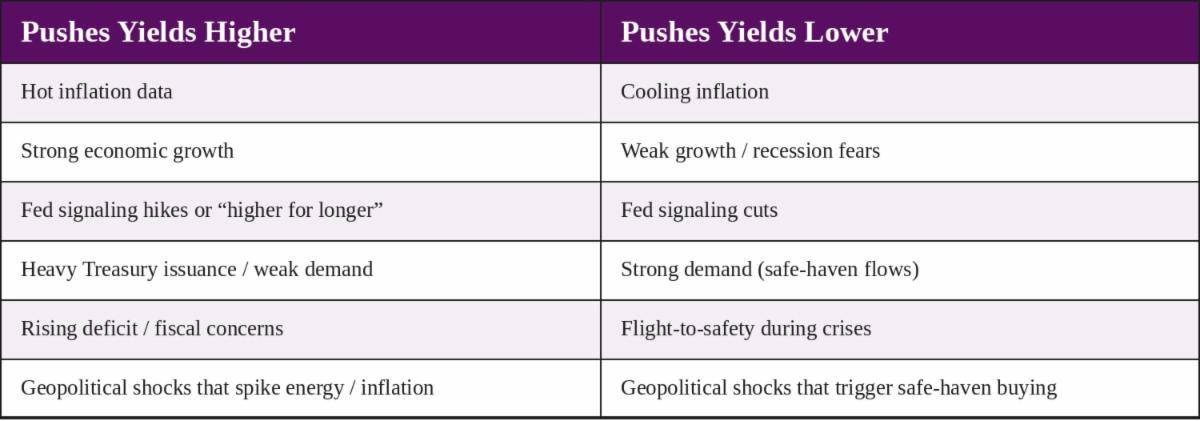
The table below presents some factors that influence the direction of Treasury bond yields.

Source: Moore Financial Advisors

Bond Market Current Issues

It is a fact that yields have pushed higher in the US, as well as in other countries, this year.

From a low point of 3.9% in early January 10-Year Treasury yields climbed nearly a percentage point, to 4.78% in early September.

Short-term Treasury Bond and Bill yields are also up by about a percentage point and currently sit at about 4.0%.

It’s also true that for many investors, returns for high quality intermediate and long-term bond funds have fallen short of expectations in 2026.

The benchmark US Bloomberg Aggregate Bond Index, which is made up of thousands of high-quality issues, including US Treasuries, guaranteed mortgage-backed securities, and corporate bonds, has produced a negative return of -0.25% year-to-date as of September 4.

Financial markets experts point to several factors behind the increase in yields, including:

  • investors’ concerns that inflation is too high
  • central banks around the world aren’t doing enough to contain inflation
  • governments are acting in fiscally irresponsible ways by running large, successive deficits – particularly since the pandemic

These are valid concerns and could lead to more upward pressure on bond yields in the future, but do not point to imminent crisis.

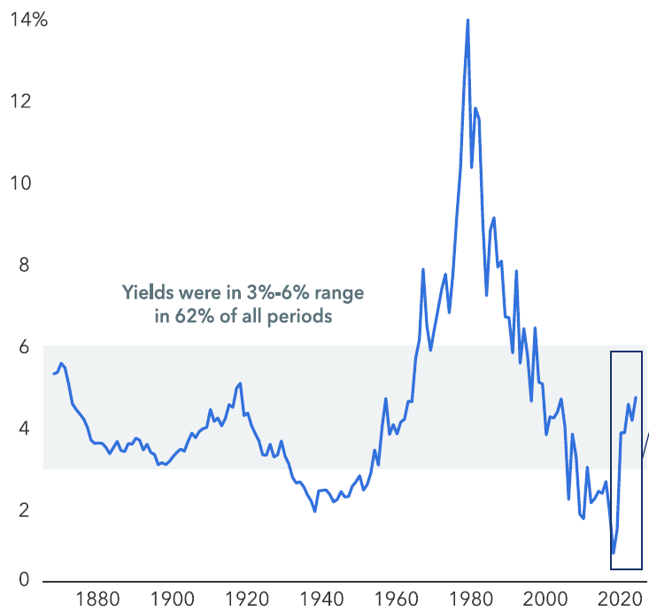
Courtesy of Capital Group, the chart below shows a 155-year history of long-term Treasury bond yields going back to 1871. 

Source: Capital Group

Prior to 1962, the data represents the average long-term government bond yield; from 1962 forward, the data represents 10-Year Treasury yields as of December 31 each year within the period.

The data shows that 62% of the time, long-term Treasury bond yields fall within a range of 3% to 6%.

When bond yields move out of this range, it’s a strong possibility that something may be amiss in the economy or the financial markets.

In the 1970s and 1980s, the US economy was stressed by energy shocks, rolling recessions, and elevated inflation, which pushed interest rates well above the normal band to record high levels.

In the 15 years following 2006, the US economy was challenged by fallout from a global financial crisis (2008-2009) and a pandemic (2020) which pulled interest rates well below the normal band to record low levels.

Today’s interest rates, when viewed through a long-term historical lens, sit comfortably in the middle of the normal band.

According to analysis done by JP Morgan asset management, 10-year Treasury yields have averaged 5.7% since 1958. A 10-year yield approaching 4.8% is hardly indicative of “crisis”, “shock”, or “havoc”.

To some extent, modestly higher yields can be considered good news for bondholders.

With stock markets at record highs, the rise in yields reflects a resilient global economy that can absorb higher borrowing costs. And higher yields mean investing in bonds today will deliver more income over time.

Why Hold Bonds in Your Portfolio?

Even though the environment for bond investors has been challenging for most of 2026, the main reasons for owning high-quality bonds, including US Treasuries, remain intact:

  • Bonds provide recurring, dependable income
  • Investment-grade bonds with near- to intermediate-term maturities are less volatile than stocks, and can help stabilize a portfolio when financial markets become unsettled
  • Shorter-maturity bonds and bond funds are typically a good source of “liquidity” and convert easily to cash when money must be withdrawn from a portfolio

The bottom line: the sky is not falling in bond-land.

The unsatisfactory returns many investors have experienced in their bond allocations year to date likely have been counterbalanced by satisfactory returns from their stock allocations.

Also, sub-par bond returns this year are coming on the heels of above-average returns for bonds last year.

This return experience is normal and indicative of a generally healthy economic and financial market environment.

For most individual investors, an allocation to bonds is, and will continue to be, an important component of a well-diversified portfolio.

-RK

August 2026 Market Recap:

This month’s financial market commentary has been kept purposefully brief. We’ve provided a separate article entitled Is the Sky Falling in Bond-land? that goes into more depth about developments in the bond market. (You will see that article in our next blog post.)

Resilient corporate earnings were the main development that supported the stock market in August.

Earnings reports for the second quarter ended June 30 in aggregate turned out to be much better than anticipated and far better than last year.

For example, Nvidia, the maker of chips used in AI data centers (and currently the largest company in the US when measured by stock market value) announced stellar results in late August.

But what really caught the attention of investors was Nvidia’s forecast that strong sales growth would continue well into next year.

With most large, publicly traded companies having released their results for second quarter, 76% exceeded analysts’ expectations.

Sales in the second quarter of 2026 were up 15% compared to the same period last year, and earnings were up by 32%.

The month of August was generally positive for both stocks and bonds, reversing the weak performance experienced by most market segments in July.

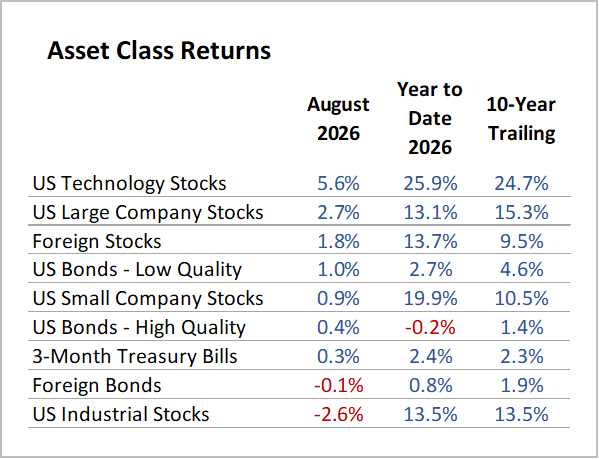
US Technology stocks led the way with a 5.6% increase. Large company US stocks did well, rising by 2.7%, and foreign company stocks weren’t far behind, with an increase of 1.8%. Small company US stocks struggled to keep pace but still generated positive performance of 0.9%.

Gains in the US bond market were more muted, but still generally positive, with high-quality bonds returning 0.4%, and US Treasury bills up 0.3%. Foreign bonds were the laggard, declining by a modest 0.1%.

Here are results for August and 2026 Year-to-Date, compared to longer-term annualized returns (10-Year Trailing):

Source: Morningstar

-RK