Category

The Outlook for Social Security – An Update

In our August 2025 letter, MFA founder Susan Moore provided an in-depth overview of Social Security’s financial outlook — including the projected timeline for trust fund depletion, what it could mean for your benefits, and what proposals were circulating in Washington.

Much has happened since then. This month, we bring you up to date on the latest official projections and the new policy developments that are reshaping the Social Security picture.

The 2026 Trustees Report: A Closer Look at the New Numbers

On June 9, 2026, the Social Security Board of Trustees released its annual report on the financial health of the program. The headline finding: the retirement trust fund is running out faster than previously thought.

The Old-Age and Survivors Insurance (OASI) Trust Fund — the fund that pays retirement and survivor benefits — is now projected to be depleted in the fourth quarter of 2032. That is one year earlier than the 2033 estimate we reported last August.

At that point, if Congress has not acted, the Social Security Administration would be able to pay only 78% of scheduled retirement benefits — an automatic, across-the-board cut of 22%.

The broader Social Security system — which includes disability benefits — tells a somewhat more nuanced story. The Disability Insurance (DI) Trust Fund remains healthy and is projected to be able to pay full benefits through at least 2100.

If Congress were to allow the retirement and disability funds to share reserves (as it has done in the past), the combined depletion date would extend to 2034, at which point 83% of combined benefits would be payable.

Why Did the Outlook Get Worse?

Three factors drove the worsened projections this year:

  1. Lower fertility rates. The trustees lowered their estimate of the long-run fertility rate to 1.75 children per woman, down from 1.9 in last year’s report. Fewer births today mean fewer workers paying into the system decades from now.
  2. Reduced immigration. The projections also reflect lower assumed levels of net immigration going forward. Immigrants make up a meaningful portion of the workforce paying Social Security payroll taxes, so fewer workers coming into the country translates directly into less revenue for the program.
  3. The “One Big Beautiful Bill Act.” This legislation, enacted on July 4, 2025, made permanent the lower income tax rates from the 2017 Tax Cuts and Jobs Act and added a new deduction of up to $6,000 for taxpayers age 65 and older who meet certain income thresholds. While these provisions benefit many retirees in the short term by reducing their tax bills, they also reduce the revenue flowing into the Social Security trust fund from the income taxation of benefits. The Committee for a Responsible Federal Budget estimates that the legislation alone accounts for roughly one-quarter of the worsened 75-year actuarial shortfall.

Taken together, these factors pushed Social Security’s projected 75-year shortfall to approximately $30 trillion, up from $26 trillion last year — a 16% deterioration in a single year.

What Would a 22% Benefit Cut Actually Mean?

For context, here is how a 22% reduction would translate for beneficiaries across different income levels. These are generalized examples; actual amounts depend on individual earnings history and claiming age.
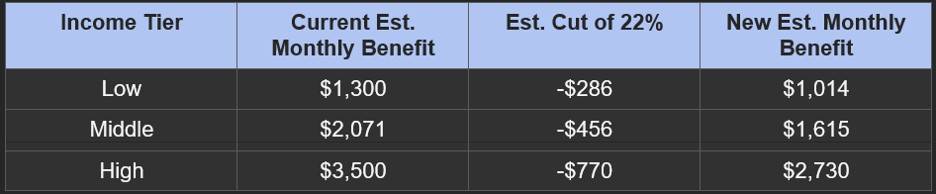
For married couples, the impact would be even more pronounced. A couple where both spouses receive average benefits could see their combined Social Security income drop by roughly $10,600 per year.

What About Current Retirees?

This remains the question we hear most often. The short answer is: current retirees are not immune, but they remain the least likely to be affected by any deliberate policy change.

Here is the important distinction to keep in mind. There are two ways benefits could be reduced:

  • An automatic cut triggered by trust fund depletion — which, under current law, would affect all beneficiaries, current and future alike, starting in 2032.
  • A deliberate legislative change — which historically has protected current retirees. Congress has never reduced benefits for people already collecting, and most reform proposals continue to focus changes on future retirees or phase them in gradually over many years.

So the risk facing current retirees is not primarily that Congress will cut their benefits on purpose. The risk is that Congress will fail to act at all, allowing the automatic trust fund depletion mechanism to take effect.

What Is Being Proposed to Address This?

Despite the urgency, Congress has not yet passed any Social Security reform legislation. The political obstacles remain formidable: meaningful fixes require either higher taxes, lower benefits, or some combination of both — none of which is easy to sell to voters. That said, the debate is becoming more active.

Some of the ideas being discussed include:

  • Raising the Full Retirement Age (FRA) from the current 67 to as high as 69. This would effectively reduce lifetime benefits, particularly for those with shorter life expectancies, even without an explicit benefit “cut.”
  • Lifting the payroll tax cap. Currently, wages above $184,500 (2026) are not subject to Social Security payroll taxes. Raising or eliminating this cap is one of the most commonly cited ways to improve the program’s finances.
  • Means-testing and income-based reductions. Some proposals would reduce benefits or slow cost-of-living adjustments for higher-income retirees while preserving or increasing them for lower earners.
  • Supplemental investment funds. Senators Bill Cassidy (R-LA) and Tim Kaine (D-VA) have put forward a bipartisan proposal that would create a new parallel investment fund, seeded with approximately $1.5 trillion in federal borrowing, to supplement payroll taxes over a 75-year horizon.

No plan has been signed into law. But there is growing acknowledgment on both sides of the aisle that action cannot be deferred indefinitely.

As one analyst at the Brookings Institution noted recently, the window for solutions is narrowing: every year of inaction reduces the available options and leaves less time to phase in changes in a way that gives workers and retirees adequate time to prepare.

Should I Change My Claiming Strategy?

For those of you who have been delaying benefits to maximize your age-70 payout, the question of whether to claim early — to “lock in” benefits before any potential cuts — continues to come up.

Our guidance remains consistent with what we shared in August:

  • There is no clear reason to change course yet. The rules are unchanged, and delayed claiming still earns you an 8% annual increase in benefits between Full Retirement Age and age 70.
  • Claiming early does not protect you from an automatic trust fund cut, which would affect all beneficiaries regardless of when they started collecting.
  • Any deliberate legislative change is still most likely to be structured to protect current beneficiaries, or at minimum to phase in changes gradually.
  • We continue to recommend basing your claiming decision on your individual circumstances — longevity, tax situation, income needs, and overall financial plan — rather than speculation about policy outcomes.

If there is a sudden, significant policy change that alters this calculus, we will be in touch promptly.

What This Means for Your Financial Plan

The 2026 Trustees Report confirms what prudent financial planning has already accounted for: Social Security’s future is uncertain, and a degree of conservatism is warranted.

Here is how we are thinking about this for our clients:

  • For clients currently receiving benefits, we do not recommend making immediate changes to your plan. We are monitoring the situation closely.
  • For clients approaching retirement, we continue to model your plan with a margin of safety that factors in the possibility of modest benefit reductions over time.
  • For younger clients, Social Security remains part of our planning picture — but not the whole picture. We generally assume a conservative benefit level in projections, which means your portfolio and other savings carry more weight.

-SM
Market Update June 2026: Halftime in Football & Finance

To my gridiron-wired mind, aspects of the “other football” are curious and bemusing.

For example:

  • The clock counts up, not down, and keeps running during stoppages, resulting in time mysteriously tacked on at the end of the game
  • Ties are allowed, considered normal – and often celebrated
  • Flopping appears to be a legitimate tactic
  • Offside: a player can be offside without touching the ball: simply interfering with an opponent’s ability to play – blocking their line of sight, for example – while in an offside position can be deemed a violation
  • Cards: penalty cards accumulate across games: get two yellow cards in separate matches and a player can be suspended for the next match
  • Advantage Rule: a referee can see a clear foul happen and simply not blow the whistle, waving play on because the fouled team already has the ball in a good position
  • Substituted players can’t return: once you’re subbed off, you’re done for the match

Fortunately, World Cup games include a break that allows for reflection, discussion with more soccer-savvy acquaintances, and, if necessary, online search to figure out what transpired during the past 45 minutes of play.

Thank goodness for halftime.

Since we’ve reached the halfway point of the calendar year, it’s appropriate to reflect on some of the key developments in the financial markets so far in 2026:

  • AI: Enthusiasm for Artificial Intelligence (AI) and the ecosystem that supports its development has been a driving force behind demand for technology stocks
  • Earnings: Strong first-quarter earnings reports from large US companies, along with upward revisions to earnings forecasts, have also helped to buoy stocks
  • War: US-Iran conflict caused severe dislocation in the oil trade, but the geopolitical shock was short-lived for US investors
  • Inflation: It has remained sticker than hoped – well above the Federal Reserve’s 2% target – keeping bond yields elevated
  • The Fed: Leadership change at the Federal Reserve has shifted the interest rate policy outlook – new Fed Chair Kevin Warsh has signaled a firm commitment to bringing inflation back to 2%, raising the odds of Fed rate hikes later in the year
  • SpaceX: The company’s Initial Public Offering (IPO) created a major market event – it was the biggest IPO in history. The rocket-satellite-AI company became the sixth largest firm globally and it demonstrated investor interest for new, tech focused companies.
  • Stock market leadership is broadening beyond technology: after years of tech stock dominance, industrials, financial institutions, healthcare, and small-company stocks began participating more meaningfully in June, a sign often associated with a healthier bull market.

The phenomenon mentioned in the last bullet point has been labelled “The Great Rotation” by some Wall Street commentators.

For more than a decade, a highly concentrated group of very large technology-oriented

companies has driven positive stock market performance.

However, the massive amounts of spending tech companies are now undertaking to actualize their AI-related plans is coming under greater scrutiny by investors.

If the pundits are correct in their characterization of this emerging “rotation” situation, investors have started pulling money out of the “expensive” tech stocks and redeploying that cash into less expensive areas of the market.

The result of a typical rotation is that money stays in the stock market, leadership changes, and positive overall stock market performance continues.

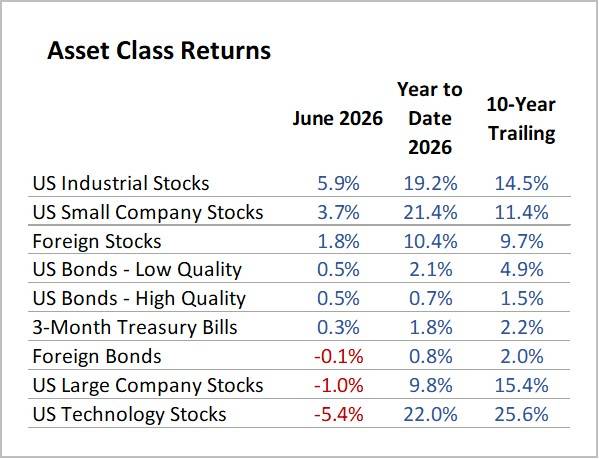
Thus far in 2026, stocks of all shapes and stripes are having another good year, as the middle column in the table below indicates.

But take a closer look at the June data in the left-hand column. US Industrial stocks top the list in performance of the Asset Class Returns table.

The Industrials index, made up mostly of “old economy stocks” – companies such as Caterpillar, Boeing, Union Pacific (railroads), and Eaton (electrical equipment) – outpaced the Technology index (which includes Nvidia, Broadcom, and Meta) by more than 10 percentage points last month.

Note: YTD 2026 as of 6/30/2026; Source: Morningstar

And two other non-tech sectors, Healthcare (+11.5%) and Financials (+9.7%) had even stronger performance in June than Industrials.

One month of old economy stocks outperforming new economy stocks fails to indicate a true “Great Rotation”.

But the shifting of preferences and performance displayed in June are noteworthy and may be a positive sign for the stock market as a whole – and for investors who maintain broadly diversified portfolios.

-RK

A Richer Retirement

Bill Bengen was a financial planner in the early 1990s who confronted the question that often puzzles aspiring retirees: “When I get to retirement, how much can I spend?”

For his baby boomer clients at the time, there was little expert guidance on the subject. Bengen decided to investigate himself, and in 1994 published his findings in the Journal of Financial Planning under the title Determining Withdrawal Rates Using Historical Data.

The article demonstrated that a 4% initial withdrawal rate from a tax-advantaged account had never failed to allow the account to last for at least 30 years, based on data going back to 1926. And thus, the “4% Rule” was born.

Bengen continued to refine his research. His 2025 book, A Richer Retirement: Supercharging the 4% Rule to Spend More and Enjoy More, argues for a new “4.7% Rule”.

Importantly, Bengen reminds retirees that inflation is their “greatest enemy” and emphasizes that retirees must consistently adjust their withdrawals for the higher cost of living.

Bengen’s book is foundational for financial planners and will be of interest to individuals who want to explore the research behind the 4% Rule.

Bengen was recently interviewed by Morningstar, and you can listen to the discussion on the May 19 episode of Morningstar’s The Long View podcast.

You Got the Bill for College – Now What?

That envelope (or email) from the college bursar’s office is coming. Maybe it’s already sitting in your inbox. And if you’ve never seen a college tuition bill before, the first reaction is usually some version of shock — even when you know well ahead of time that the number was coming. 

So let’s talk about what to do before you just write the check.

First, Understand What You’re Actually Looking At

A college billing statement isn’t always straightforward. You’ll see tuition, room and board, fees — but you’ll also see credits for financial aid, scholarships, and loans.

Before you do anything, make sure the aid package you were promised is actually reflected on the bill.

Missing scholarships or grants happen more than you’d think, and a quick call to the bursar’s (or business) office can save you thousands. Many bills are confusing. Ask if you don’t understand what you are looking at.

Second, Think Before You Tap That 529

If you have a 529 plan, this is the moment you’ve been saving for — but timing matters. A few things to keep in mind:

  • Distributions need to match qualified expenses in the same calendar year to stay tax-free
  • Room and board counts — but only up to the school’s published cost of attendance figures
  • If your student received a scholarship, you could withdraw that same amount from the 529 with no penalty — though the earnings portion may still be subject to income tax
  • Be sure the funds go directly from your custodian to the student’s account with the bursar at the college

Third, Consider the Payment Plan

Most schools offer an installment payment plan — typically spreading the semester bill over 4-6 months for a small enrollment fee (usually $50-100). In my experience, this is one of the most underused tools in college financing.

Why pull a lump sum from investments or a 529 all at once when you can spread it out and keep your money working a little longer?

Or, see if there is any room in your monthly income to make payments in place of a loan (or lower your loan). This can be a significant savings, yet many families often look at financing as “all or nothing.”

When you actually have the option, choose a payment plan that fits your budget and allows you to make regular payments to the college out of your monthly cash flow. It is wise to do so if you are able and lower any debt you may be considering as often your 529 is not going to cover the balance for four years.

Finally, Don’t Ignore the Loans Conversation

If federal loans are part of your plan, they don’t just appear — your student needs to accept them through the financial aid portal.

They also have documents to sign such as a promissory note required for the funds to be disbursed to the school. It sounds obvious, but I’ve seen families miss disbursements simply because no one clicked “accept.”

Check that box now and have your student watch for emails from financial aid on documents needed.

Think about this: the families who navigate college costs most successfully aren’t always the ones with the most money. They’re the ones paying attention in June and July, before the bill is actually due.

So take action NOW so you are prepared and ready for fall – and enjoy some relaxing time with your college student who is home for summer!

-DC

How Much Can You Spend in Retirement?

Two of the more common questions Susan, Donna, and I hear as planners are of vital importance for those thinking about their financial future are:

  • “How do I know if I have enough saved for retirement?”
  • “How much can I safely spend each year without running out of money?”

These are questions without a simple universal answers. But there are two powerful tools that can help: the 4% rule, a well-known rule of thumb rooted in decades of research, and a personalized probability of success analysis, which we build for our clients using financial planning software.

In this article, we want to explain both measures — where each comes from, what it can tell you, and how they can work together to give you a more complete picture of your retirement readiness.

The 4% Rule: A Historically-Grounded Starting Point

The 4% rule was developed in 1994 by financial planner and researcher William Bengen, who set out to answer a question that no one had systematically studied before: what is the maximum amount a retiree can withdraw each year without running out of money?

Rather than guessing about future market returns, Bengen turned to history.

He studied the actual investment returns and inflation data for every quarter going back to January 1926, and reconstructed what would have happened to someone who retired on a specific date, withdrew a set percentage of their savings in their first year, then adjusted that dollar amount for inflation every year thereafter — similar to how Social Security’s cost-of-living adjustment works.

Bengen studied hundreds of historical retirees, asking: what is the highest withdrawal rate that would have worked for all of them, including those who retired at the worst possible moments in market history?

Results of Bengen’s Study

The answer: 4% (and with a more diversified portfolio, up to 4.7%). A retiree who withdrew 4% of their starting portfolio value in year one, then adjusted that dollar amount for inflation each subsequent year, would have maintained their portfolio for at least 30 years regardless of when in history they retired — through the Great Depression, the stagflation of the 1970s, the dot-com crash, and the 2008 financial crisis.

In plain terms, a retiree with $1,000,000 in savings could withdraw $40,000 in their first year. If inflation ran at 3% that year, they would take $41,200 in year two, and so on. According to this framework, they would not have run out of money over a 30-year retirement, even in the worst historical environments.

Here’s something important that often surprises people: the 4% rule was calibrated to the single most difficult retirement outcome in nearly a century of data — a retiree who started in October 1968 and faced both a severe bear market and a prolonged period of high inflation. That one cohort ended their 30-year retirement with essentially nothing left.

For virtually every other retiree in history following the same 4% rule, portfolios not only survived — they grew.

Many retirees ended their 30 years with substantially more wealth, in real terms, than they started with. The long-run average across all historical retirees was closer to 7%, meaning most people could have withdrawn nearly double the 4% rate without running out of money.

What the 4% Rule Does Well

  • Grounded in real history, not assumptions about the future
  • Provides a quick, memorable benchmark: ff you’re withdrawing less than 4% of your savings each year, you’re in a strong position historically speaking
  • Reflects actual worst-case scenarios — the kinds of markets and inflation environments that genuinely tested retirees

What It Doesn’t Capture

Bengen himself is clear that the rule was never meant to be a universal prescription and that treating it as one is itself a problem. Because the rule is calibrated to a single worst-case cohort, applying it universally causes most retirees to spend far less than they safely could.

In a recent Morningstar interview, Bengen described the 4% rule as applying only to a very narrow set of circumstances — specifically, retirees facing both high inflation and very high stock market valuations simultaneously — and stressed that most people can do considerably better with a personalized approach.

Beyond the underspending risk, your retirement situation is unique in ways the 4% rule doesn’t account for:

  • Your tax situation. Withdrawals from taxable accounts are subject to capital gains and income taxes that can meaningfully reduce your spending power — potentially requiring a more conservative withdrawal rate.
  • Your timeline. If you retire at 60 and live to 95, you need your money to last 35 years, not 30. A longer time horizon calls for a lower initial withdrawal rate.
  • Your specific goals. Whether you intend to leave an inheritance, cover long-term care costs, or adjust your spending significantly over time all affect what’s appropriate for you.
  • Current market conditions. Bengen’s research shows that safe withdrawal rates are closely tied to stock market valuations. With today’s market valuations on the higher end of the historical range, the future may look somewhat different than the historical average.

A Note on Inflation

Bengen calls inflation “the greatest enemy of retirees”.

Unlike a market downturn, which typically recovers, sustained high inflation forces retirees to take larger and larger withdrawals over time – accelerating the depletion of their savings.

This is one reason why we pay close attention to inflation trends in general, and specifically for your financial plan. It’s also why a regular review of your plan is recommended.

Probability of Success: Your Personalized Financial Plan

While the 4% rule provides a useful starting point, your financial plan is designed to go much further — and its central metric (in the RightCapital financial planning software that we use with our clients) is called the Probability of Success.

How It Works

The Probability of Success represents the percentage of simulated futures in which your plan does not run out of money during your lifetime.

Here’s how it’s calculated: The software runs 1,000 separate simulations of your financial future. Each simulation uses a different random sequence of investment returns and inflation rates, all drawn from historical market behavior.

One simulation might reflect a scenario similar to the 1970s stagflation; another might mirror the strong markets of the 1990s; another might look like a prolonged downturn shortly after you retire.

After all 1,000 simulations are complete, the software counts how many ended with money still in your plan. If 870 out of 1,000 simulations ended with a positive balance, your Probability of Success is 87%.

What Score Should You Be Aiming For?

We typically target a Probability of Success in the range of 80% to 90% for our clients. Here’s why we find that range to be an appropriate outcome:

  • A score above 90% is a sign of strength, but it can also indicate that you’re spending less than you could comfortably afford. If your score is very high, it may be worth discussing whether you could increase your spending, give more to family or charity, or retire earlier.
  • A score between 80% and 90% means your plan is well-positioned. It has weathered the most stressful simulated environments with a strong success rate.
  • A score between 70% and 80% suggests the plan could benefit from some adjustments — whether to spending levels, savings, retirement timing, or portfolio allocation.
  • A score below 70% is a signal that more significant changes may be needed.

A plan that succeeds in 100% of simulations is typical one that is very conservative, often meaning you’re spending significantly less than history suggests you could.

We recognize that for some clients, this level of conservatism is preferable. For those clients who have plans with the strongest outcome, though, thinking more expansively about approaches to spending may also merit consideration.

What Makes Your Score Go Up or Down?

Your Probability of Success is driven by the specific details of your plan, including:

  • Your annual retirement spending. This is typically the most powerful lever. Modestly reducing planned spending can meaningfully improve the score; increasing it has the opposite effect.
  • When you retire. Delaying retirement by even a year or two can improve the score significantly, both by extending the savings period and by shortening the distribution period.
  • Your portfolio allocation. The mix of stocks, bonds, and other assets affects both expected returns and the volatility of those returns across simulations.
  • Sources of guaranteed income. Social Security, pensions, and annuities all reduce the amount your portfolio needs to provide and tend to improve the score.

How These Two Tools Work Together

The 4% rule and your Probability of Success analysis are not competing measures, rather they complement each other, and each is better suited to a different stage of the planning conversation.

Think of the 4% rule as a compass. Before you’ve built your full financial plan, it can quickly orient you: is your situation in the right ballpark?

A prospective retiree withdrawing 3% of their savings annually has significant flexibility; one withdrawing 7% faces real constraints under almost any methodology. That early directional read is genuinely useful.

Your financial plan — and its Probability of Success — is the detailed map.

Once we know your full picture, including your income sources, taxes, goals, timeline, and spending patterns, we can build a plan that reflects your life, not a historical generalization. The probability score becomes the primary measure we track and revisit together over time.

What Both Measures Agree On

Despite using different methodologies, these two approaches are grounded in the same body of evidence about financial markets and inflation.

Bengen himself notes that his historical approach and Monte Carlo simulation generally produce similar conclusions — which is reassuring, since they’re studying the same underlying dynamics.

Both measures also point to the same warning signals:

  • A sustained rise in inflation is the condition most likely to require a meaningful reduction in withdrawals. Unlike a temporary bear market, persistent inflation continuously forces higher withdrawals, accelerating portfolio depletion.
  • A significant market decline early in retirement can have an outsized impact on the long-term health of a plan — which is why we pay special attention to portfolio construction and risk management in the years just before and after retirement.

What This Means for You

Our goal in building and maintaining your financial plan is to give you clarity and confidence — the freedom to spend, give, and live in retirement without unnecessary anxiety about money.

One of the most important things that a personalized plan can reveal is that you might have more flexibility than a simple rule of thumb suggests. Both the 4% rule and your Probability of Success are tools in service of that goal.

Here’s what we recommend for our clients:

  • Review your plan at least annually. Markets change, your spending changes, and your goals evolve. Your Probability of Success should be re-evaluated regularly in light of these changes.
  • Don’t panic at temporary market declines. History shows that most bear markets recover, and plan adjustments made in the heat of a market downturn often do more harm than good. We’ll help you assess whether any action is truly needed.
  • Take inflation seriously. If the inflation environment changes meaningfully, it’s worth a conversation about your withdrawal plan.
  • Think about your full-time horizon. Many people underestimate how long their portfolio may need to last. We encourage our clients to build in a margin of safety by planning for a longer retirement than average life expectancy.

If you’d like to review your current Probability of Success, discuss your withdrawal strategy, or simply talk through how your plan is positioned for the environment ahead, we’d love to hear from you. That’s exactly what we’re here for.

-RK

May 2026 Market Recap: The Everything Rally

ASteve Sosnick, the chief market strategist at Interactive Brokers, referred to financial market activity in May as “the Everything Rally.” That’s not a bad way to frame what happened last month.

At the start of the month, investors were confronted with an unsigned Iran peace deal, oil above $100, inflation at a three-year high, a brand-new Federal Reserve chair, and a 30-year Treasury yield touching its highest level since 2007.

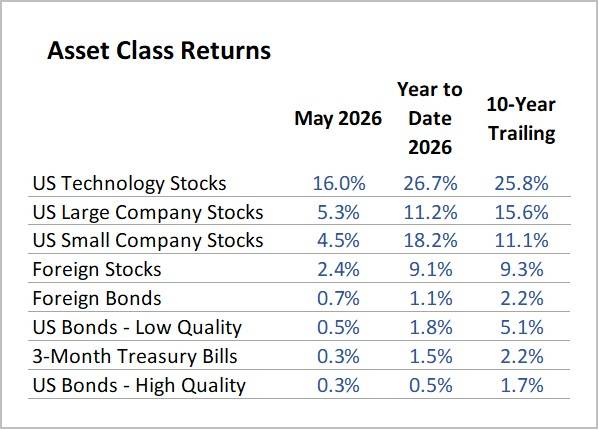
May closed with Technology sector posting another double-digit monthly gain. The S&P 500 index of large company US stocks rose 5.3% and closed at record highs on 11 days during the month. Foreign stocks gained more than 2.4%, and bond indices (despite large intra-month swings in yields) registered modest positive returns.

May was defined by three themes: the Iran war and its economic consequences; AI delivering broad-based, positive revenue trends in the technology sector; and a bond market that tested investor nerves.

The Iran War — Deal Always “Just Around the Corner”

The U.S.-Iran conflict is now in its fourth month. The Strait of Hormuz remained largely closed to commercial traffic, with only a handful of ships transiting daily versus 120 before the war.

Oil prices swung dramatically on diplomatic signals: Brent crude peaked near $126 in late April, fell toward $87 by month-end, then traded at various points in between as headlines shifted from hope to frustration and back again.

The month’s diplomatic arc was a recurring pattern: a constructive signal would arrive, sending oil sharply lower and stocks higher — only to be followed by a complication. By month-end, the memorandum of understanding between the US and Iran remained unsigned, and June opened with the same central question May had posed: when will a deal be signed?

The economic consequences of the conflict were visible throughout the month. Inflation hit 3.8% year-over-year — its highest since 2023 — driven heavily by energy. National average gas prices remained above $4.50 per gallon for most of the month.

And Goldman Sachs and Barclays both cautioned that even if the Strait fully reopened tomorrow, global oil inventories are so depleted that prices likely would normalize only gradually, not immediately.

Artificial Intelligence Delivers Positive Revenue Trends

April validated that AI is driving positive financial results for chip makers. May confirmed that AI demand is broadening into other areas of the technology ecosystem.

Some examples of how AI-driven demand is benefiting tech companies:

  • Dell Technologies, which many folks associate with personal computers, reported AI server revenue up 757% year-over-year, a record $51.3 billion AI order backlog, and raised its full-year revenue forecast by roughly $27 billion.
  • Cisco, another “old-line” technology-focused company, known for its networking gear that supports internet activity, raised its full-year AI order guidance to $9 billion — nearly double what it had guided just one quarter earlier.
  • Nvidia, the new tech standard bearer that designs chips, and also hardware networks to power data centers as well as specialized software, reported $81.6 billion in quarterly revenue — up 85% year-over-year — and guided its next quarter to $91 billion.
  • Cerebras Systems, which delivers supercomputer systems and cloud-based services, listed its shares through the largest tech initial public offering (IPO) since Uber went public in 2019, saw its shares surge 68% on the first day of trading.

The broader AI narrative for the month was captured well by one market analyst: “We started with chips and memory, but it’s really now about the broad AI infrastructure stack.”

And more AI-related activity is in store for investors in the months ahead, with SpaceX, Anthropic (maker of Claude) and OpenAI (maker of ChatGPT) all expecting to list their shares through IPOs and being trading on stock market exchanges later this year.

The Bond Market’s Warning

Not everything pointed straight up in May.

The bond market delivered a warning mid-month that temporarily interrupted the equity rally. The 30-year Treasury yield approached 5.2% in mid-May – its highest level since 2007, before the financial crisis – and the 10-year Treasury yield approached 4.7% (though bond yields did decline in the back half of May).

The main driver of higher yields was the Iran war’s inflationary impact on energy prices globally. The practical consequence for US households: 30-year fixed mortgage rates climbed back to 6.68%, putting further pressure on an already-stalled housing market.

Adding to the complexity, Kevin Warsh took over as Federal Reserve Chair on May 15, inheriting a divided institution with inflation running well above its 2% target.

The probability of a Fed rate hike in 2026, which was essentially zero a month ago, climbed as high as 45% during the month. Warsh’s first formal interest rate policy decision comes June 16.

Despite the swings in yields, benchmark US bond indices delivered positive returns in May. High quality bonds returned 0.3% for the month, and low quality bonds rose 0.5%.

As June begins, the questions that defined May remain open. The Iran deal is unsigned. Inflation remains elevated. The new Fed chair faces his first policy decision with rate-hike odds that would have seemed unthinkable a few months ago.

And yet the stock market enters June at all-time highs, with US Large Company Stocks up 11.2% for the year and Foreign Stocks up 9.1%. Whether the optimism that has driven the fourth consecutive year of stock market gains (so far) proves durable is the central question for the months ahead.

Here are results for May and 2026 Year-to-Date, compared to longer-term annualized returns (10-Year Trailing):

Note: YTD 2026 as of 5/31/2026; Source: Morningstar

-RK

More Than Enough

Even if you think of yourself as having “enough” rather than “more than enough,” if you are spending at a conservative rate from your savings, the reality is that you may well be unlikely to deplete your assets during your lifetime. Which means that, financially speaking, “enough” might turn out to be “more than enough.”

In More Than Enough: A Brief Guide to the Questions That Arise After Realizing You Have More Than You Need, author Mike Piper provides a framework for how to approach the “problem” of having more financial resources than you may need.

Topics include:

  • Do you have more than enough?
  • Who gets the money?
  • Talking with your kids and other heirs
  • Giving and spending during your lifetime
  • Learning to spend and give more

The value in Piper’s short book is not that it provides an answer key for solving the more-than-enough “problem”. Instead, for those who have saved well and lived within their means, it poses questions for self-reflection and introduces ideas that individuals may wish to consider in conjunction with their advisors, including tax professionals, estate planning attorneys, and financial planners.

Piper is a Missouri Licensed CPA, and the author of several personal finance books and the blog Oblivious Investor.

The Real Cost of Switching Majors

Choosing a major at the age of 17 or 18 is usually not easy – and switching majors in college is common. In fact, most students change their major two to three times before graduating.

While this is sometimes necessary and a healthy way to explore interests, families are often unaware that it can have a major impact on graduation date and overall cost. It is usually not a consideration in the planning process for college financing prior to choosing a college.

The potential increase in cost may not be a reason to dismiss the thought of changing majors especially if it will truly be a better path for the student. However, it is wise to anticipate the potential changes in cost and time to graduation.

Here is what to consider when talking about potential major changes.

Lost Time- Extra Semesters

This can be the biggest factor in changing majors. Adding extra semesters involves more cost.

Many majors have different core requirements and sequences of courses. Switching into a specified major such as nursing, engineering, or education for example requires foundational courses that are often different for each. Changing to a very different major can create the need for:

  • An additional semester
  • An additional full year
  • Sometimes certain courses are only offered one semester per year

We all know college costs are high, and an extra semester can cost anywhere from $12,000-$25,000 or possibly much more depending on the school.

Losing Credit for Courses Already Taken

Families often assume that if a student stays at an institution, prior coursework will apply to a change in major, but that is not always the case.

A change in major can cause:

  • Electives that no longer satisfy major requirements
  • Lost credit toward major prerequisites
  • Credits that count toward graduation, but not the new degree

Program GPA Requirements

Many competitive majors require higher GPAs for admission to the program and if admission is delayed, students may not be able to enter the program later, or may be required to retake courses or take courses that do not count toward graduation.

Effects on Scholarships and Financial Aid

Some scholarships are tied to:

  • Being in a specific major
  • Taking a minimum number of major-related credits
  • Tuition waivers- tied to majors
  • Departmental Awards- tied to majors

Emotional Impact: Pressure, Stress and Confidence

Considering the financial impact matters of course, but there are the emotional impacts on the student to consider:

  • Exploring career options in high school
  • Getting involved as a volunteer or in a program or business that you are interested in
  • Speaking to adults in your family and friend circle who work in your desired profession
  • Consider self-interests and not just popular majors
  • Your first year in college- find a great advisor and take advantage of their expertise and advice

All this information is not to say that switching majors is a sign of poor planning or failure, but rather to encourage consideration early in the process to help avoid some of the potential challenges and costs later.

The bottom line is that with the significant investment in a college education it is important for students to be in a major that will help them lead a successful and happy career after graduation.

Guide to Retirement Accounts in 2026

Every year, the IRS adjusts contribution limits for retirement savings accounts to keep pace with inflation. For 2026, those adjustments are meaningful across nearly every account type — good news for anyone working to build their financial future.

But the more important story is not the numbers themselves. It is understanding which accounts are available to you, how each one is taxed, and how to stack them intelligently based on your income, your employment situation, and how close you are to retirement.

This article is designed to serve as a practical reference. In the first section, we walk through the major tax-advantaged retirement accounts — who can use them, what the tax benefits are, and how the 2026 limits compare to 2025.

We also cover an important new rule under the SECURE 2.0 Act that took effect this year and affects catch-up contributions for higher earners in 401(k) plans.

In the second section, we bring these accounts to life through three case studies, each featuring a married couple at a different stage of life, earning a different level of income, but each with the same goal: to save ten percent of their gross household income for retirement.

As you will see, there is no single formula that works for everyone. But there is almost always a combination of accounts that can get you there in a way that is tax-efficient — and 2026 is a particularly good year to review your strategy.

Part I: The Accounts

401(k) Plans

Who is eligible. A 401(k) plan is sponsored by your employer, so eligibility depends on whether your workplace offers one. Most full-time employees at companies that sponsor a 401(k) can participate, typically after a short waiting period. Self-employed individuals can establish a Solo 401(k), which provides access to essentially the same contribution limits.

There is no income ceiling for participating in a 401(k), though highly compensated employees — generally defined as those earning more than $160,000 in 2026 — may face additional restrictions if the plan fails certain nondiscrimination tests.

Tax benefits. Traditional (pre-tax) 401(k) contributions reduce your taxable income in the year they are made. The money grows tax-deferred, and withdrawals in retirement are taxed as ordinary income. Roth 401(k) contributions are made with after-tax dollars, so there is no upfront deduction — but qualified withdrawals in retirement are completely tax-free. Employer matching contributions are always made on a pre-tax basis, regardless of whether you contribute to the traditional or Roth side.

2025 vs. 2026 contribution limits. The employee deferral limit increases from $23,500 in 2025 to $24,500 in 2026. The standard catch-up contribution for those ages 50 and older increases from $7,500 to $8,000, for a total of $32,500. For those in the 60–63 age window, SECURE 2.0 introduced a “super catch-up” that remains at $11,250 in 2026, for a total employee deferral of $35,750. The overall combined limit (employee contributions plus employer contributions) increases from $70,000 to $72,000 in 2026.

2026 Rule Change — Roth Catch-Up Requirement (SECURE 2.0). This is the most significant change affecting 401(k) plans in 2026, and it deserves careful attention.

Beginning January 1, 2026, employees who are age 50 or older and whose FICA wages with their employer exceeded $150,000 in the prior calendar year must make all catch-up contributions on a Roth (after-tax) basis. Pre-tax catch-up contributions are no longer permitted for this group. This provision had been included in the SECURE 2.0 Act but was repeatedly delayed. It is now in effect.

What does this mean practically? If you are 50 or older and earned more than $150,000 in FICA wages last year, your catch-up contributions this year will be directed into the Roth side of your 401(k) — with no upfront tax deduction, but with tax-free growth and tax-free withdrawals in retirement. The dollars still count toward your catch-up limit; only the tax treatment changes.

There is an important administrative wrinkle: if your plan does not offer a Roth option, it may not be able to accept catch-up contributions from affected employees at all. If you are in this group, we recommend verifying with your HR department or plan administrator right away.

403(b) Plans

Who is eligible. A 403(b) plan is the non-profit sector’s counterpart to the 401(k). Employees of public schools, colleges and universities, hospitals, churches, and qualifying non-profit organizations are eligible. Private-sector employees are not.

Tax benefits. The structure is identical to the 401(k): traditional (pre-tax) contributions reduce current taxable income, while Roth contributions grow and are withdrawn tax-free. The same 2026 Roth catch-up rule under SECURE 2.0 applies to 403(b) plans.

2025 vs. 2026 contribution limits. The 403(b) limits are the same as the 401(k): $24,500 employee deferral, $8,000 catch-up (age 50+), and $11,250 super catch-up (ages 60–63), up from $23,500 and $7,500 respectively in 2025.

Health Savings Accounts (HSAs)

Who is eligible. To contribute to an HSA, you must be enrolled in a qualifying High-Deductible Health Plan (HDHP), must not be enrolled in Medicare, and cannot be claimed as a dependent on someone else’s tax return. If you are covered by any other non-HDHP health plan, you are also ineligible. HSAs are not limited to employees — self-employed individuals on a qualifying HDHP can contribute as well.

Tax benefits. The HSA is unique among savings vehicles in offering what is often called the “triple tax advantage.” Contributions are made on a pre-tax basis (or are tax-deductible if made directly, outside of payroll). The funds grow completely tax-free. And withdrawals for qualified medical expenses are tax-free as well. No other account in the tax code offers all three of these benefits simultaneously.

There is a fourth benefit that is often overlooked: unlike a Flexible Spending Account (FSA), HSA funds roll over indefinitely. There is no “use it or lose it” rule. A family that contributes consistently to an HSA and pays current medical expenses out of pocket can build a substantial tax-free reservoir for future healthcare costs — which, in retirement, are typically one of the largest expenses families face.

After age 65, HSA funds can be withdrawn for any purpose and are taxed as ordinary income, much like a traditional IRA. Beyond age 65, the account can also be viewed as a second IRA with a prior history of tax-free contributions – though qualified medical withdrawals remain completely tax free at any age.

2025 vs. 2026 contribution limits. For self-only coverage, the limit increases from $4,300 to $4,400 in 2026. For family coverage, the limit increases from $8,550 to $8,750. The catch-up contribution for those age 55 and older (note: HSA catch-ups begin at 55, not 50) remains $1,000, for a total family contribution of $9,750 for eligible couples with at least one spouse aged 55 or older.

SEP IRAs (Simplified Employee Pension)

Who is eligible. A SEP IRA is a powerful savings tool available to the self-employed and to small business owners. Any sole proprietor, independent contractor, freelancer, or small business owner can establish a SEP IRA. Businesses of any size may also use a SEP for their employees, though in practice it is most commonly used by those who are self-employed or who own businesses with few or no other employees.

One important distinction: in a SEP IRA, only the employer contributes. An employee cannot make their own elective deferrals as they can in a 401(k).

If the business has employees, the employer must generally contribute the same percentage of compensation for all eligible employees as for themselves. From a business owner’s perspective, this makes SEPs potentially expensive and increasingly unattractive as a business grows.

Larger businesses generally prefer 401(k) plans, which offer more flexibility – like letting employees fund their own accounts, having vesting schedules, and allowing employer matches at lower required levels.

Tax benefits. Employer contributions to a SEP IRA are fully tax-deductible. Growth inside the account is tax-deferred, and withdrawals in retirement are taxed as ordinary income. There is no Roth option for a SEP IRA.

One particularly useful feature of the SEP IRA is its flexible timing: contributions for a given tax year can be made all the way up to the tax filing deadline, including extensions. This makes the SEP IRA an excellent planning tool — a self-employed person can wait until after year-end, see what their income was, and then decide how much to contribute before filing.

2025 vs. 2026 contribution limits. The SEP IRA limit is the lesser of $72,000 or 25% of compensation in 2026, up from $70,000 in 2025. For self-employed individuals, the calculation is slightly different: the effective contribution rate is approximately 20% of net self-employment income after the self-employment tax deduction. Catch-up contributions are not permitted in a SEP IRA.

SIMPLE IRAs

Who is eligible. SIMPLE IRAs are designed for small businesses — generally those with 100 or fewer employees who earned at least $5,000 during the prior year. Both employees and the self-employed may participate. Employers who establish a SIMPLE IRA generally cannot maintain another employer-sponsored retirement plan simultaneously.

Unlike the SEP IRA, the SIMPLE IRA allows employee contributions, making it more similar in spirit to a 401(k). Employers are required to make either a dollar-for-dollar match of up to 3% of compensation, or a flat 2% non-elective contribution for all eligible employees.

One important restriction: funds withdrawn from a SIMPLE IRA within the first two years of participation are subject to a 25% penalty (rather than the standard 10%) if taken before age 59½. Participants should be aware of this two-year rule before rolling funds out of a SIMPLE IRA.

Tax benefits. Employee contributions are pre-tax and reduce current taxable income. Growth is tax-deferred, and withdrawals in retirement are taxed as ordinary income. A Roth SIMPLE option does exist under SECURE 2.0 but has not yet been widely implemented by plan providers.

2025 vs. 2026 contribution limits. The standard employee contribution limit increases from $16,500 to $17,000 in 2026. The catch-up contribution for those age 50 and older is $4,000 (increased from $3,500 in 2025). And those ages 60 – 63 can contribute $5,250 as a “super catch up” contribution.

Employers that meet certain criteria may be eligible for the higher-limit SIMPLE IRA, which increases from $17,600 to $18,100. The catch-up contribution for those age 50 and older in the higher-limit SIMPLE plans is $3,850 (unchanged from 2025).

Traditional IRAs

Who is eligible. Anyone with earned income — or a spouse with earned income — can contribute to a traditional IRA. There is no income ceiling for contributing, but the deductibility of those contributions is phased out based on income and access to a workplace retirement plan.

For 2026, the phase-out ranges for deductibility are as follows:

  • Single filer covered by a workplace plan: phase-out from $81,000 to $91,000 (up from $79,000–$89,000 in 2025)
  • Married filing jointly, contributor covered: phase-out from $129,000 to $149,000 (up from $126,000–$146,000 in 2025)
  • Married filing jointly, spouse covered but not contributor: phase-out from $242,000 to $252,000 (up from $236,000–$246,000 in 2025)
  • No workplace plan coverage: contributions are fully deductible regardless of income

Tax benefits. If your contribution is deductible, it reduces your taxable income in the year it is made. Growth is tax-deferred, and withdrawals in retirement are taxed as ordinary income. Required Minimum Distributions (RMDs) begin at age 73 for those born prior to 1960, and at age 75 for those born in 1960 and later.

2025 vs. 2026 contribution limits. The contribution limit increases from $7,000 to $7,500 in 2026. The catch-up contribution for those age 50 and older increases from $1,000 to $1,100 — the first increase to the IRA catch-up since 2006.

SECURE 2.0 indexed this amount to inflation for the first time, and 2026 marks the first year the adjustment has been triggered. Total maximum IRA contribution for those 50 and older: $8,600 in 2026. Note that this limit is combined across all personal IRAs — traditional and Roth together.

Roth IRAs

Who is eligible. Eligibility to contribute directly to a Roth IRA is subject to income limits. For 2026, the ability to contribute begins to phase out at:

  • Single filers: $153,000, and is eliminated at $168,000 (up from $150,000–$165,000 in 2025)
  • Married filing jointly: $242,000, and is eliminated at $252,000 (up from $236,000–$246,000 in 2025)

High earners who exceed these thresholds are not permitted to make direct Roth IRA contributions. However, there is no income limit on Roth conversions — and the so-called “backdoor Roth” strategy, which involves making a non-deductible traditional IRA contribution and then immediately converting it to a Roth IRA, remains available. This strategy works most cleanly when you do not have significant pre-tax IRA balances elsewhere (due to the “pro-rata rule” that applies to conversions).

Tax benefits. Roth IRA contributions are made with after-tax dollars, so there is no upfront deduction. The benefit comes on the back end: qualified withdrawals in retirement are entirely tax-free, including all investment growth. The Roth IRA is also not subject to Required Minimum Distributions during the account owner’s lifetime, which gives it significant advantages both for tax planning in retirement and for legacy purposes.

Importantly, Roth IRA contributions (not earnings) can be withdrawn at any time, for any reason, without taxes or penalties — providing a degree of flexibility that other retirement accounts do not.

2025 vs. 2026 contribution limits. The same increases apply as with the traditional IRA: $7,500 in 2026 (up from $7,000 in 2025), with a catch-up of $1,100 (up from $1,000). Again, this limit is shared across all personal IRAs combined.

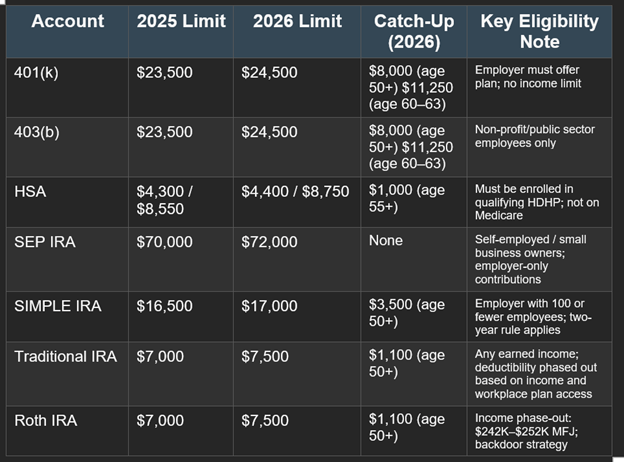
2026 Contribution Limits at a Glance

Note: 401(k) and 403(b) catch-up contributions for employees age 50+ earning more than $150,000 in FICA wages in prior year must be made as Roth (after-tax) beginning in 2026 under SECURE 2.0. Source: Moore Financial Advisors

Part II: Putting It Together — Three Case Studies

The accounts described in Part I are most useful when you can see how they work together for a real family.

The three scenarios below all share a common profile: the couple is married and filing jointly. Spouse 1 works for a company that offers both a 401(k) plan and an HSA-eligible High-Deductible Health Plan. Spouse 2 earns income as an independent contractor. And in each case, the couple is targeting retirement savings equal to 10% of their gross household income.

The income level, age, and proximity to retirement vary meaningfully across the three scenarios — and so does the optimal strategy.

Scenario 1: Building the Foundation

25 Years from Retirement • Household Income: $225,000 • Savings Target: $22,500

The income picture. Let’s assume Spouse 1 earns $150,000 in W-2 income, and Spouse 2 earns $75,000 as an independent contractor. The couple files jointly with a combined MAGI of $225,000 — which sits comfortably below the 2026 Roth IRA phase-out threshold of $242,000. That is an important and somewhat time-sensitive window: both spouses are eligible for direct Roth IRA contributions, and at age 40 they have 25 years or more for those contributions to compound entirely tax-free.

Spouse 1 — Roth 401(k) and HSA. Spouse 1 does not need to max out the 401(k) to hit the household savings target — but the type of contribution matters. Because they have 25 years until retirement and are still in a moderate tax bracket, the Roth 401(k) is the preferred vehicle: contributions are after-tax today, but every dollar of growth over the next quarter-century and into retirement will be completely tax-free at withdrawal.

The HSA deserves equal emphasis. With a 25-year time horizon, the HSA should be thought of not as a medical spending account, but as a stealth retirement account with a triple tax advantage. If the couple enrolls in a qualifying HDHP and maximizes the family HSA contribution of $8,750, and pays their current medical expenses out of pocket, those dollars can grow tax-free for decades and eventually can be used tax-free for healthcare in retirement — when medical costs tend to be at their highest.

Spouse 2 — Roth IRA. For Spouse 2, the most straightforward path is a direct Roth IRA contribution. At $225,000 combined income, they qualify. The maximum contribution in 2026 is $7,500, and like the Roth 401(k) for Spouse 1, the 25-year compounding window makes the Roth treatment highly attractive. If Spouse 2 is looking to save more, a SEP IRA offers significant additional capacity — up to approximately 20% of net self-employment income, or roughly $14,000–$15,000 in this income range.

However, SEP IRA contributions are pre-tax and add to traditional IRA balances, which creates future RMD obligations. For a 40-year-old, building Roth assets now is generally the stronger long-term choice.

Reaching the $22,500 target:

  • Spouse 1, Roth 401(k): $6,250
  • Family HSA: $8,750
  • Spouse 2, Roth IRA: $7,500
  • Total: $22,500

Key insight. This couple is in a genuinely fortunate position: high enough income to save meaningfully, but still within the Roth IRA eligibility range. As income grows over the coming years, Roth IRA access may phase out, making direct contributions unavailable. Building future tax free assets aggressively now — in the 401(k), the Roth IRA, and the HSA — is a strategy that will pay dividends for decades.

Scenario 2: The Final Push

5 Years from Retirement • Household Income: $500,000 • Savings Target: $50,000

The income picture. Let’s assume Spouse 1 earns $300,000 in W-2 income, and Spouse 2 earns $200,000 as an independent contractor. Both are in the 60–63 age window. The combined MAGI of $500,000 places them well above the Roth IRA income limit — direct Roth IRA contributions are not available. However, the heightened catch-up contribution limits available to the 60–63 age group, combined with the SEP IRA’s generous ceiling, give this couple significant tax-advantaged savings capacity.

Spouse 1 — 401(k) super catch-up and HSA. At age 62, Spouse 1 is squarely in the super catch-up window. The maximum employee deferral in 2026 is $24,500, and the super catch-up for ages 60–63 is $11,250 — for a total employee contribution of $35,750. Add the family HSA contribution of $8,750 plus the age-55+ HSA catch-up of $1,000, and Spouse 1 alone accounts for $45,500 in tax-advantaged contributions.

There is an important planning note here: because Spouse 1 earned more than $150,000 in FICA wages in the prior year, the SECURE 2.0 Roth catch-up rule applies. All catch-up contributions to the 401(k) — the full $11,250 — must be made as Roth (after-tax).

This means no immediate deduction on the catch-up amount, but those dollars will grow and be withdrawn completely tax-free. Given that this couple is likely to be in a high tax bracket throughout retirement, this is not necessarily a disadvantage — but it does affect current-year cash flow planning and should be incorporated into the tax projection for the year.

Also worth noting: with only five years remaining before retirement, HSA contributions should continue to be maximized — but the couple should be aware that HSA contributions must stop when Spouse 1 enrolls in Medicare. If retirement coincides with Medicare enrollment, the HSA contribution window closes.

Spouse 2 — SEP IRA and backdoor Roth. With $200,000 in gross self-employment income, Spouse 2’s SEP IRA capacity is substantial. After the self-employment tax deduction, net self-employment income is approximately $186,000, and 20% of that produces an allowable SEP contribution of roughly $37,000. This provides a powerful pre-tax deduction on a significant portion of Spouse 2’s self-employment income.

At this income level, a direct Roth IRA contribution is not available — but the backdoor Roth strategy may still be viable. The mechanics involve making a non-deductible $7,500 contribution to a traditional IRA and immediately converting it to a Roth IRA.

The key consideration here is the pro-rata rule: if Spouse 2 has other pre-tax IRA balances (such as from a prior rollover), the conversion will be partially taxable. If the SEP IRA holds significant pre-tax assets, the backdoor Roth becomes considerably less attractive — this is a scenario that warrants careful tax modeling before proceeding.

Reaching the $50,000 target. The remarkable thing about this scenario is that Spouse 1’s contributions alone — $45,500 — nearly cover the entire household savings target. Adding even a modest SEP IRA contribution from Spouse 2 easily surpasses $50,000.

  • Spouse 1, 401(k) base deferral: $24,500
  • Spouse 1, super catch-up (ages 60–63, Roth): $11,250
  • Family HSA (+ age-55 catch-up): $9,750
  • Spouse 2, SEP IRA: $4,500 (minimum to reach target)
  • Total: $50,000

Key insight. This couple’s actual tax-advantaged savings capacity far exceeds their 10% target. The SEP IRA alone could shelter an additional $30,000+ of self-employment income. In the five years before retirement, maximizing pre-tax deductions now — while simultaneously building Roth assets through the mandatory Roth catch-up — positions the couple with diversified tax exposure in retirement. That tax diversification, between taxable and tax-free income sources, will give them meaningful flexibility to manage their tax bracket after they stop working.

Scenario 3: Extending the Runway

Spouse 1 Retired • Spouse 2 Still Working • Household Earned Income: $75,000 • Savings Target: $7,500

The income picture. This scenario is different in kind from the first two. Spouse 1 is retired — perhaps drawing from a pension or investment portfolio — and has no earned income. Spouse 2 is still working as an independent contractor, earning $75,000. The household’s total earned income — the figure that governs retirement account eligibility and contribution limits — is Spouse 2’s $75,000 alone.

The couple’s combined MAGI is well below the Roth IRA income phase-out threshold, which means both Roth IRA strategies and Roth conversions carry a favorable tax cost.

Spouse 1 — The spousal IRA. Although Spouse 1 has no earned income of their own, a spousal IRA allows Spouse 2’s earned income to fund a contribution on Spouse 1’s behalf. As long as the couple files jointly and Spouse 2 has sufficient earned income, Spouse 1 can contribute up to $7,500 — or $8,600 with the catch-up if age 50 or older — to either a traditional or Roth IRA in their own name.

At the income level in this scenario, a Roth IRA is the recommended choice for Spouse 1. The current tax rate is likely lower than it will be if and when larger RMDs kick in from pre-tax accounts. Every dollar contributed to the Roth IRA now will grow and be withdrawn tax-free. There are no RMDs on a Roth IRA during the account owner’s lifetime, which provides additional planning flexibility.

The Roth conversion opportunity. This scenario also presents one of the most powerful Roth conversion windows available: the period after one spouse has retired but before RMDs begin and Social Security is claimed at its full level.

If Spouse 1 has significant pre-tax balances in a former employer’s 401(k) or in traditional IRAs, the gap years of early retirement — when taxable income is lower — are an ideal time to convert portions of those accounts to Roth IRAs. For a more detailed discussion of this strategy, including the interaction with Social Security and Medicare premiums, please see our April 2026 article on Roth conversions.

Spouse 2 — SEP IRA and Roth IRA. Spouse 2 has two natural vehicles: a SEP IRA for the immediate tax deduction on self-employment income, and a Roth IRA for tax-free future growth.

The maximum SEP contribution here is approximately 20% of net self-employment income — roughly $14,000 at this income level. Since the household savings target is $7,500, Spouse 2 does not need to maximize the SEP IRA; instead, the question is how to split the contribution between tax-deferred (SEP) and tax-free (Roth).

If Spouse 2 is enrolled in a qualifying HDHP and is not yet on Medicare, an individual HSA contribution of $4,400 (plus $1,000 if age 55 or older) is also available, offering additional tax-advantaged capacity.

Reaching the $7,500 target:

  • Spouse 1, spousal Roth IRA: $7,500 (or $8,600 with catch-up)
  • Spouse 2, Roth IRA: Additional $7,500 if desired (funded by Spouse 2’s earned income)
  • Spouse 2, SEP IRA: Optional — for additional tax deduction on self-employment income beyond the 10% target

To meet just the $7,500 target, the simplest path is a single spousal Roth IRA contribution for Spouse 1. But this couple has the capacity to do considerably more if they wish — and given the favorable income level and tax environment, doing more in Roth form is likely to serve them well.

Key insight. This scenario illustrates something that surprises many clients: a retired spouse can still build retirement savings, as long as the other spouse has earned income and the couple files jointly.

The spousal IRA is underused and underappreciated. Combined with the Roth conversion opportunity that retirement creates — often a multi-year window of lower taxable income before RMDs and Social Security crowd the picture — this couple has the tools to meaningfully strengthen their tax position in retirement, even on a modest income.

Closing Thoughts

The 2026 contribution limit increases are welcome news — they give savers a bit more room. But the greater opportunity lies in understanding how these accounts work together. A 401(k) and an HSA and a Roth IRA and a SEP IRA are not competing options. For the right family, they are complementary layers of a single, coherent strategy — each account doing a specific job, in a specific tax “bucket,” for a specific purpose.

The right combination for your family depends on your income, your employment situation, your age, your proximity to retirement, and your tax picture today versus what you expect it to be in the future. There is no one-size-fits-all answer — which is exactly why we model these decisions individually, account by account, year by year.

If you have not recently reviewed how your current contributions are structured, or if your situation has changed — a new job, a shift to self-employment, a spouse entering or leaving the workforce, or an approaching retirement — this is an ideal time for a conversation. We are here to help you make the most of every dollar you put to work for your future.

April 2026 Market Recap: One Strong Month

April proved to be an exceptionally strong month for the stock market.

The month opened against the backdrop of an active shooting war, a nearly closed Strait of Hormuz, record oil prices, and a consumer confidence reading at an all-time low. Despite these concerns, stocks powered forward setting new all-time highs.

April was defined by three themes: diplomacy; an earnings season that delivered; and artificial intelligence producing revenue results for big technology companies.

The first theme was diplomacy — messy, uncertain, but seeming to trend in the right direction, from a financial markets standpoint.

April’s arc ran from President Trump threatening to knock out “every power plant and every bridge” in Iran, to a Pakistan-brokered ceasefire, to Iran briefly opening the Strait and then closing it again, to a revised Iranian proposal arriving through mediators on the final day of the month.

None of it was clean, and no permanent deal was reached. But markets are forward-looking, and as each week passed, the probability of catastrophic escalation fell while the probability of an eventual resolution rose. That directional shift — even without a final outcome — was enough to send stocks marching to new all-time highs.

The second theme was an earnings season that delivered, broadly and convincingly.

By month’s end, roughly 87% of S&P 500 companies that reported had beaten Wall Street analysts’ earnings estimates, with first-quarter profit growth tracking above 13% year-over-year.

A few of the standouts:

  • Intel posted the largest earnings surprise — as a percentage — ever recorded for a major index component, sending the stock up 23% in a single session
  • Caterpillar stock jumped 10% on a blowout quarter and raised full-year guidance
  • Apple closed the season with record iPhone and Services revenue, announcing a $100 billion stock buyback, and Q3 guidance more than double what analysts had expected

The message from corporate America was consistent and clear: revenue and profits are generally on an upward trend and business is resilient.

The third theme was artificial intelligence — not as a concept, but as a revenue reality.

Several of the largest technology companies in the world showed impressive financial results related to AI infrastructure: Google Cloud grew 63% year-over-year, Microsoft’s Azure accelerated to 40% growth, and Amazon Web Services posted its fastest growth rate in 15 quarters. These were not promises about future potential — they were current-quarter revenue numbers from businesses already running at tens of billions of dollars in annual revenue.

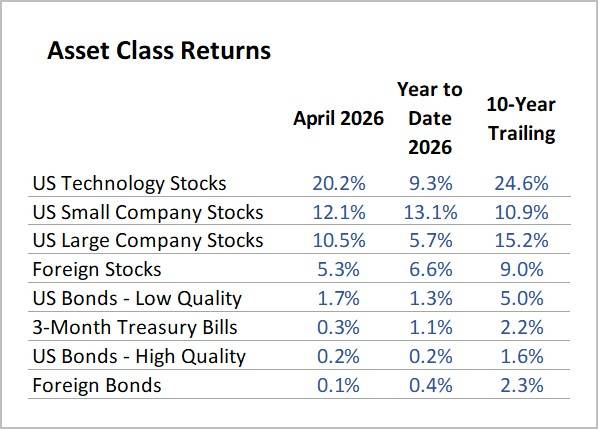
Here are results for April and 2026 Year-to-Date, compared to longer-term annualized returns (10-Year Trailing):

Note: YTD 2026 as of 4/30/2026; Source: Morningstar